
MCA Reverse Consolidation: How It Works and What to Review
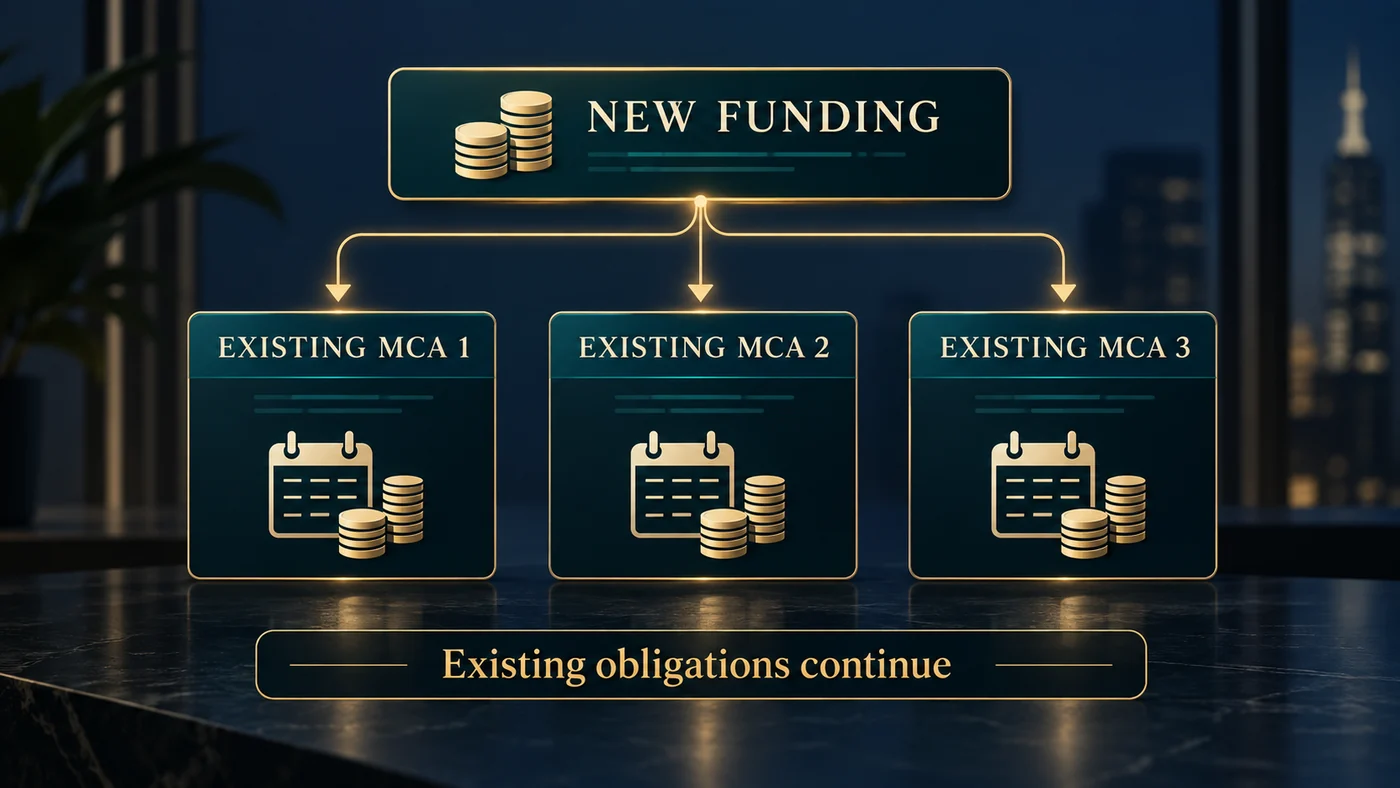
Reverse consolidation usually means new funding delivered over time to help cover existing MCA withdrawals. It may reduce the immediate cash leaving your business, but it does not necessarily pay off the old advances. Review both the promised deposits and every payment obligation before treating it as relief.
You have several merchant cash advances pulling money from the same account. A new provider offers weekly deposits to help you keep up, in return for another payment arrangement. The sales pitch focuses on what you will save this week. The decision also depends on what you will owe next month—and what happens if the next deposit never arrives.
“Reverse consolidation” is a product label, not a substitute for reading the agreement. Providers may structure their offers differently. The funding schedule, conditions and written obligations determine how a particular offer works.
How does an MCA reverse consolidation work?
In a typical installment-funded arrangement, the new provider sends money to the business periodically while the existing MCA companies continue collecting their payments. The business also owes payments under the new agreement. The old balances run down only as the original funders receive and credit money.
That differs from a payoff consolidation, where new financing is used to satisfy identified existing balances at closing. Before relying on a claim that several MCAs will become “one payment,” identify which funders will actually be paid off, when, and what written releases or termination documents will follow.
There is no reliable rule that every reverse consolidation provides 20–25% extra cash, follows the same weekly schedule or lasts longer than every original advance. Use the figures in your offer. Our MCA debt consolidation guide compares funding with negotiated legal options.
Follow the money through one week
Consider this simplified example. It illustrates cash movement, not a quote or a typical offer.
| Transaction | Amount |
|---|---|
| Existing MCA withdrawals | −$5,000 |
| New provider’s scheduled deposit | +$4,000 |
| Payment to the new provider | −$1,500 |
| Net cash leaving the business | $2,500 |
The business uses $2,500 of its own cash that week instead of $5,000. That is temporary cash-flow relief, not $2,500 of debt forgiveness. The new agreement creates a separate obligation that must be included in the overall comparison.
If the $4,000 deposit does not arrive while both sets of scheduled withdrawals remain due, the same week could require $6,500. Actual obligations and remedies depend on the agreements and circumstances. Deposit timing matters too: money arriving Friday may not cover withdrawals earlier in the week.
The critical risk: later funding may be conditional
Ask whether the provider is contractually committed to every scheduled installment and what permits it to suspend, reduce or terminate funding. Conditions may involve account activity, revenue, returned payments, additional financing or compliance with other terms. Read those provisions alongside the default and repayment language.
If funding stops, the original MCA obligations do not disappear merely because you expected the new provider to cover them. You may also have a dispute about amounts already advanced, fees or the remaining obligation under the new contract.
Get the proposed funding schedule in writing. Keep the signed agreement, actual deposit records, withdrawal history and communications about any missing installment. An advertised total funding amount should not be confused with money already received or an unconditional commitment to disburse it.
Compare the whole arrangement, not just a smaller payment
- Existing balances: Obtain current payoff figures and identify which original contracts remain in place.
- New cash actually available: List each scheduled deposit, deductions, fees and conditions for receiving it.
- Total new obligation: Separate the amount advanced from the amount purchased or repayable and any additional charges.
- Overlapping payments: Map original withdrawals and new payments on the same calendar, including the period after installments stop.
- Early payoff: Ask for the written calculation and any discount conditions. Do not assume either that early payment saves money or that no offer ever allows a discount.
- Security and guarantees: Review new MCA UCC provisions, personal guarantees, default triggers and any restrictions in the existing agreements.
A factor rate describes a cost calculation; daily or weekly describes a collection schedule. Changing the payment frequency does not, by itself, reduce the total cost.
The useful comparison is what your business pays and receives across the full schedule under each option. Test that schedule against realistic revenue, including a slower month, rather than assuming sales will improve enough to make the new obligation affordable.
Review options before adding another MCA obligation
Depending on the agreements and business facts, alternatives may include a contractual reconciliation request, a negotiated payment change, settlement discussions or legal review of an existing dispute. None automatically stops collections or requires a funder to accept a proposal.
If you already have a lawsuit or a restraint affecting your account, address the legal papers and response deadlines separately. A funding application or negotiation does not itself pause a court case.
Business Debt Law Group reviews MCA agreements, payment disputes and related lawsuits. Bring the proposed reverse-consolidation agreement together with the existing MCA contracts and schedules so the overlapping obligations can be assessed. Consultations are always free. The firm provides legal services; it does not offer consolidation financing. Request My Free MCA Review.
This article provides general information, not legal or financial advice for a particular transaction. Product terms, legal rights and outcomes depend on the agreements, applicable law and individual circumstances. Reading this article does not create an attorney-client relationship.
Free MCA Review or Case Evaluation
Have questions about your MCA agreements, payment pressure, or court papers? You do not need a lawsuit to request a free review.
Consultations are free; retained legal-service fees are separate. Contacting the firm does not create an attorney-client relationship or extend a deadline. No outcome is guaranteed.