
How to Choose MCA Help: Attorney Fees and Lawsuit Defense
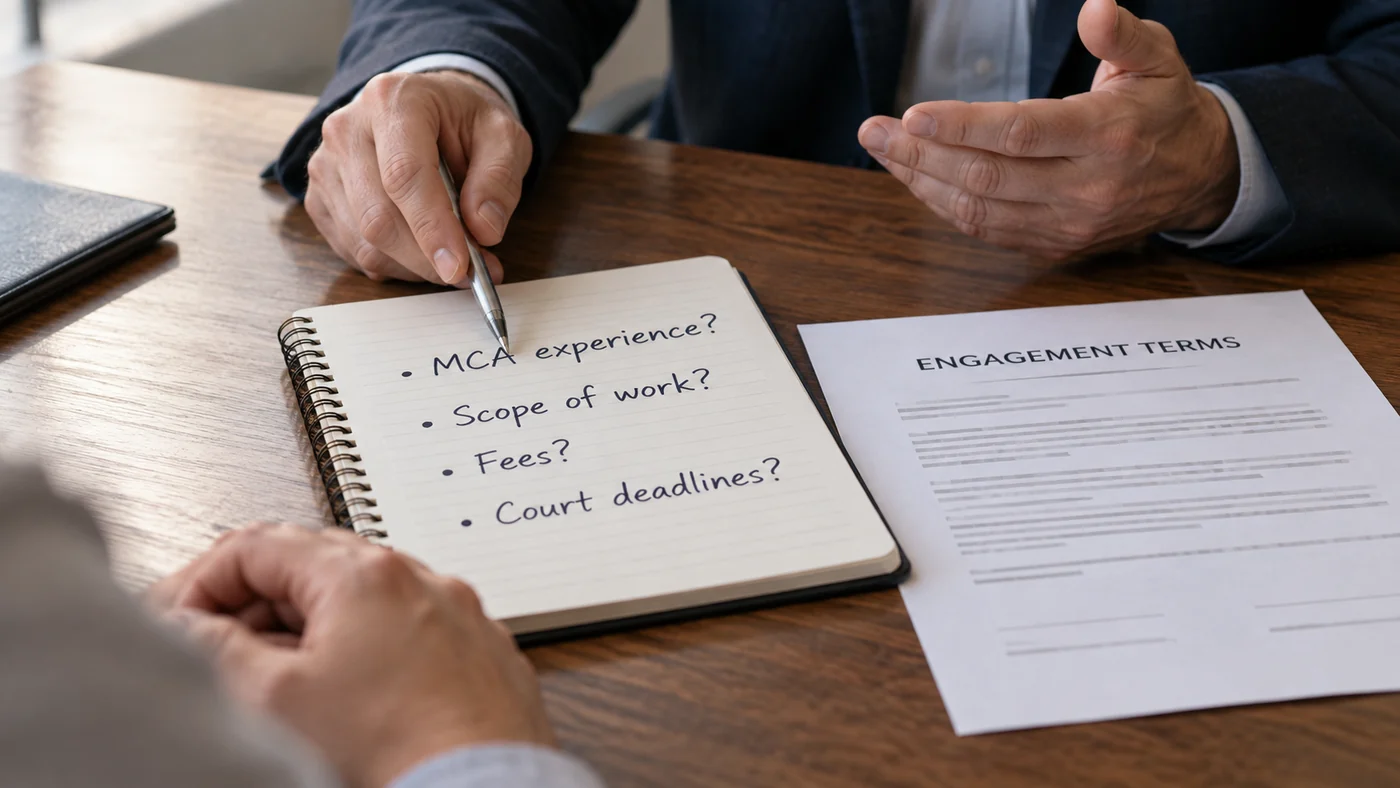
Before hiring help for an MCA problem, find out who will do the work, what the fee covers and who is responsible if a funder files suit. Price alone cannot answer those questions.
An owner facing several daily withdrawals may hear competing offers from settlement companies, funding brokers and law firms. Similar promises can describe very different services. “We handle your MCA debt” might mean negotiating with a funder, arranging another advance, collecting money toward a possible settlement, or representing you in a lawsuit.
A useful comparison begins with a written scope of work. You should be able to explain what you are buying without relying on the salesperson’s assurances.
Should I hire a merchant cash advance attorney?
If the issue involves a lawsuit, a disputed guarantee, a restraint on funds, an MCA UCC demand or the meaning of an MCA contract, legal advice may be important. A merchant cash advance attorney can evaluate those legal issues and explain which services the firm is able to provide in the relevant jurisdiction.
A negotiation service is not automatically an attorney-client relationship. Ask who represents you, whether that person is licensed where needed, and whether litigation is included in the engagement. The phrase “attorney backed” does not answer those questions.
If you have already been served, provide the complete court papers and service details at the outset. Signing up for a settlement program or scheduling a consultation does not itself extend your deadline to respond.
Our merchant cash advance attorney guide explains the types of legal issues that may need attention.
Ask for these answers before paying
- Who is my provider? Obtain the contracting entity’s name, the responsible lawyer’s name if legal services are offered, and a direct contact for questions.
- Which MCAs are included? List every funder and agreement covered. Ask whether the business, owner or both are clients and how potential conflicts are handled.
- What work is included? Distinguish document review, negotiations, reconciliation requests, court appearances, discovery, motions, appeals and enforcement work.
- What happens if I am sued? Identify who will review service, enter an appearance where appropriate and handle deadlines. Ask whether a separate engagement or local counsel is required.
- What will I pay? Get the fee structure, payment dates, expenses, cancellation terms and any additional charges in writing.
- How will I see progress? Ask how often you will receive updates and copies of written proposals, agreements and relevant court filings.
You can check an attorney’s public licensing record with the applicable state bar or attorney-registration authority. Verify the individual lawyer, not merely a logo or a claim that a company has lawyers somewhere in its network.
Separate service fees from money intended for creditors
If a program asks you to make one payment to cover several MCAs, request a written breakdown. Identify how much pays the provider, how much is held for possible settlements, and how much actually reaches each funder.
Ask who holds the money, in whose name the account is maintained, who can withdraw it and when unused funds can be returned. The answers should match the signed agreement and account statements.
A deposit into a program account is not necessarily a payment to a creditor. A creditor payment is not necessarily a settlement. And negotiations do not mean a funder has agreed to stop collecting or suing.
Before relying on a proposed resolution, obtain written terms identifying the accounts, payment schedule, treatment of guarantees and liens, release obligations and consequences of a missed payment. Keep proof of amounts actually received and credited by the funder.
Low fees and high fees both need context
A limited engagement can be appropriate when its boundaries are clear. For example, a fee for reviewing a complaint or preparing a particular filing may exclude later hearings, discovery or settlement negotiations. The issue is whether you understand that limit and have a plan for the rest of the case.
A higher fee does not guarantee better work, a longer case or a favorable result. Compare the proposed services, lawyer responsibility, relevant experience, communication and total expected expense. Ask how the engagement changes if the matter becomes more complicated.
Be wary of promises that a particular filing buys a fixed number of months of “safety.” Court schedules and outcomes depend on the case, the applicable procedures and the judge’s rulings. Litigation work should respond to legitimate legal issues, not be sold as guaranteed delay.
Warning signs in an MCA relief pitch
- A guaranteed settlement percentage before anyone has reviewed the agreements or spoken with the funders.
- An instruction to stop every payment without discussing the contracts, business facts and litigation risks.
- A promise that enrollment automatically stops a lawsuit, bank restraint or creditor communication.
- A refusal to identify the lawyer who will be responsible for an existing case.
- Unclear allocation of your payments between fees, reserves and creditor distributions.
- A new advance described as debt reduction without a clear explanation of which existing balances will actually be paid off.
None of these questions requires you to accept a sales pitch on the spot. Request the proposed agreement and read it alongside the written answers. If a representative promises something important, ask where it appears in the engagement.
What to expect from a free BDLG consultation
Bring a list of MCA funders, the signed agreements, current withdrawals and any legal notices. Tell us whether your immediate concern is an unaffordable payment schedule, a collection demand or a filed lawsuit. That distinction helps identify the work that may be needed.
Business Debt Law Group focuses on merchant cash advance disputes and related legal matters. We can discuss the available scope of assistance, representation arrangements and potential next steps based on your situation. Consultations are always free. If you choose to retain the firm, the services and fees will be addressed separately in an engagement agreement.
For a comparison of funding and workout approaches, see MCA consolidation or an attorney. For an active case, start with the MCA lawsuit guide.
This article is general information, not advice about a particular provider or case. No attorney-client relationship arises from reading it or requesting information. Outcomes, required services and fees depend on the matter and the written engagement.
Free MCA Review or Case Evaluation
Have questions about your MCA agreements, payment pressure, or court papers? You do not need a lawsuit to request a free review.
Consultations are free; retained legal-service fees are separate. Contacting the firm does not create an attorney-client relationship or extend a deadline. No outcome is guaranteed.