When are Merchant Cash Advances Loans? When Do They Cross the Line?
Is a merchant cash advance a loan? An MCA may be structured as a purchase of future business receipts, but its name does not settle its legal treatment. The central question in a loan-classification dispute is whether the funder actually takes the risk that the purchased receipts will not materialize, or instead has an absolute right to repayment.
That distinction can matter when a business challenges an MCA as a usurious loan. It does not mean that every expensive advance is unlawful, or that finding one unfavorable clause cancels the agreement. The contract must be read as a whole.
This guide examines legal classification, rather than comparing financing products. The court decisions below apply New York law; they illustrate the issues without establishing a rule for every state. An attorney must identify the law governing the particular transaction.
Start with the risk: what happens if the receipts never arrive?
A purchase of future receipts exposes the purchaser to uncertainty about those receipts. An obligation to pay back the advance regardless of business revenue points toward a loan. Calling the document a “receivables purchase agreement” cannot substitute for examining its actual obligations. New York’s LG Funding decision explains that courts look at the transaction’s substance and the agreement as a whole.
For a business owner, the useful question is concrete: if sales fall for an ordinary business reason, do the payment obligation and collection period genuinely adjust, or must the business still deliver the full amount on the same schedule? Answering that requires reading the payment terms alongside the default provisions and any guarantee.
Three contract features that help answer the question
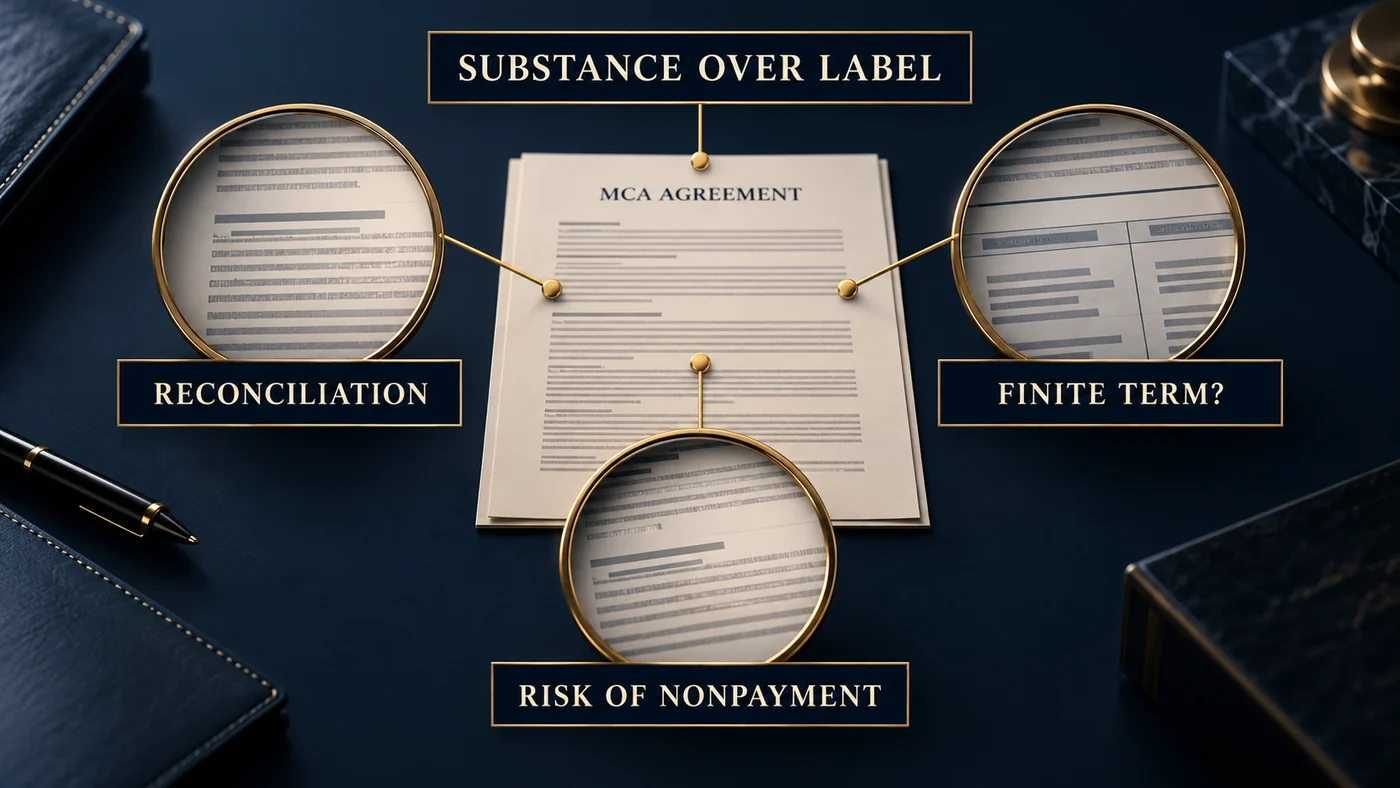
New York appellate courts commonly examine reconciliation, the length of the repayment obligation and the funder’s recourse if the merchant files bankruptcy. These are factors to weigh together, not a scorecard that mechanically decides a case.
1. A real adjustment right
A reconciliation provision can connect collections to actual receipts. Its effect depends on the terms: does the funder have to make the contractual adjustment when the merchant meets the requirements, or can it refuse entirely at its own discretion? Simply including a paragraph headed “reconciliation” does not answer that question.
Fixed daily withdrawals can be estimates subject to adjustment; their presence alone does not establish a loan. K9 Bytes v. Arch Capital Funding illustrates why the adjustment mechanism matters. The separate MCA reconciliation guide explains the request process.
2. A deadline that survives a sales decline
Distinguish an expected collection period from a binding deadline. If the agreement permits smaller collections as receipts decline, the completion date may move. A fixed maturity requiring payment regardless of receipts points in a different direction. In Principis Capital v. I Do, adjustable payments and an indefinite term supported the court’s conclusion that the transaction was not a loan.
3. Recourse triggered by bankruptcy
Read what the bankruptcy provision actually triggers. Does filing make the remaining purchased amount immediately due or activate a personal guarantee? Those rights can suggest that the funder has shifted the risk of business failure back to the merchant or owner. A bankruptcy-default clause does not, by itself, establish that the entire transaction is unlawful.
In Kapitus Servicing v. Suburban Waste Services (2026), the appellate court found competing indications in the agreements. Bankruptcy recourse suggested a loan, while the absence of a definite term suggested contingent repayment; the reconciliation right was unclear. The court left classification unresolved rather than declaring the agreements loans as a matter of law.
A personal guarantee: what exactly did the owner promise?
The important distinction is between guaranteeing particular contractual obligations and guaranteeing repayment regardless of what happens to the receipts.
A performance guarantee may cover specified promises or conduct. An unconditional repayment guarantee can require the owner to pay even when the business generates no receipts. Read the triggering events and the amount covered, including provisions incorporated from the main agreement. The heading on the guarantee is not enough.
A guarantee does not automatically turn an MCA into a loan: the agreement upheld in Principis included a personal guarantee of performance. Conversely, the New York trial court in Phantom Advance v. Top House Properties considered a guarantee triggered by insolvency or bankruptcy, together with discretionary reconciliation, in finding a loan. These outcomes show why the scope of the promise matters.
Closing the business does not establish a release
A genuine loss of future receipts is different from an alleged breach of contractual promises. A business closure therefore calls for an examination of why operations ended, whether purchased receipts remain, what the agreement defines as a default and whether a guarantee is triggered. Do not assume that closing the doors settles those questions or releases the owner. Classification and liability must be assessed under the actual agreement and facts.
Loan classification, usury and the remedy are separate questions
First, classification: is the transaction legally a loan? Then, legality: does that loan violate an applicable rule? Finally, remedy: what relief or defense does the law provide on the evidence presented?
A loan can be lawful. A merchant cash advance usury defense requires more than identifying loan characteristics: counsel must assess the applicable interest rules, the treatment of fees and other charges, the amount and parties involved, relevant exceptions and the required proof.
The consequences can be substantial when usury is established. In Adar Bays v. GeneSYS ID, New York’s highest court held that a loan proved criminally usurious under the law at issue is void, with principal and interest uncollectible. That holding does not mean every MCA, every personal guarantee or every disputed payment is unenforceable. Nor does spotting a concerning term establish a successful defense or guarantee a favorable settlement.
Get a focused review of the repayment obligation
If you suspect your MCA functions as a loan, ask counsel to identify the specific provisions that make repayment absolute or contingent, how those provisions interact, and the legal significance of the payment history. A useful assessment should explain both the argument and its limitations.
Business Debt Law Group can review your agreement, guarantees and dispute with you. Request My Free MCA Loan Review or call 888.695.3547. Consultations are always free; fees for retained legal services are addressed separately.
This article provides general legal information, not advice about a particular agreement. Laws, contract terms and facts differ. Reading this article or requesting a consultation does not create an attorney-client relationship. Do not change payments, close a business or disregard legal papers based solely on this article.
Free MCA Loan Review or Case Evaluation
Have questions about your MCA agreements, payment pressure, or court papers? You do not need a lawsuit to request a free review.
Request My Free MCA Loan Review
Consultations are free; retained legal-service fees are separate. Contacting the firm does not create an attorney-client relationship or extend a deadline. No outcome is guaranteed.