Reliant Funding Lawsuit or MCA Payment Plan?
A lower monthly payment does not explain the whole settlement. Review who can approve the agreement, what is due upfront and whether the remaining schedule is sustainable.
Free MCA review or case evaluation.
No lawsuit is required to ask for help.
The Reliant file
The redacted payment-plan agreement in BDLG’s library identifies Reliant Funding as the original creditor. That wording matters: an original creditor, a current holder and the party collecting payments do not necessarily perform the same role.
Start with the name on the signed agreement and compare it with the demand, proposed settlement and any complaint. Ask for the documents supporting another party’s authority when those names differ. The business should know whose claim is being settled and who can provide the promised release.
Reliant’s current public website uses Reliant Funding branding within an LCF Ventures web address. That current presentation does not identify the legal counterparty to every historical agreement. Review your own documents, including renewals or later assignments, without substituting today’s branding for the name actually used in your matter.
Sources: Reliant Funding’s current website
- Designation in the example
- Reliant Funding is listed as original creditor.
- Structure shown
- Initial wire payment followed by monthly installments.
- Distinct review issue
- Authority to settle, upfront affordability and release after completion.
- Independent legal representation
- Business Debt Law Group is not affiliated with, endorsed by, or acting for Reliant Funding.
The down payment matters as much as the monthly number.
The redacted agreement lists $67,800 in settlement terms against a $96,285.84 balance. It calls for a $15,000 initial wire followed by monthly payments of $2,030.76 until the settlement amount is paid. It addresses default consequences and a release after the required payments. The excerpt does not establish completed performance.
See more MCA settlement examples ↗
Partial, redacted excerpt from one matter. Other pages, amendments and later events may affect these terms. This discussion does not summarize the complete agreement or case. Acceptance, completed payment, releases and the final outcome require verification from the complete records. This is not a standard offer or promised result. Past results do not guarantee a similar outcome.
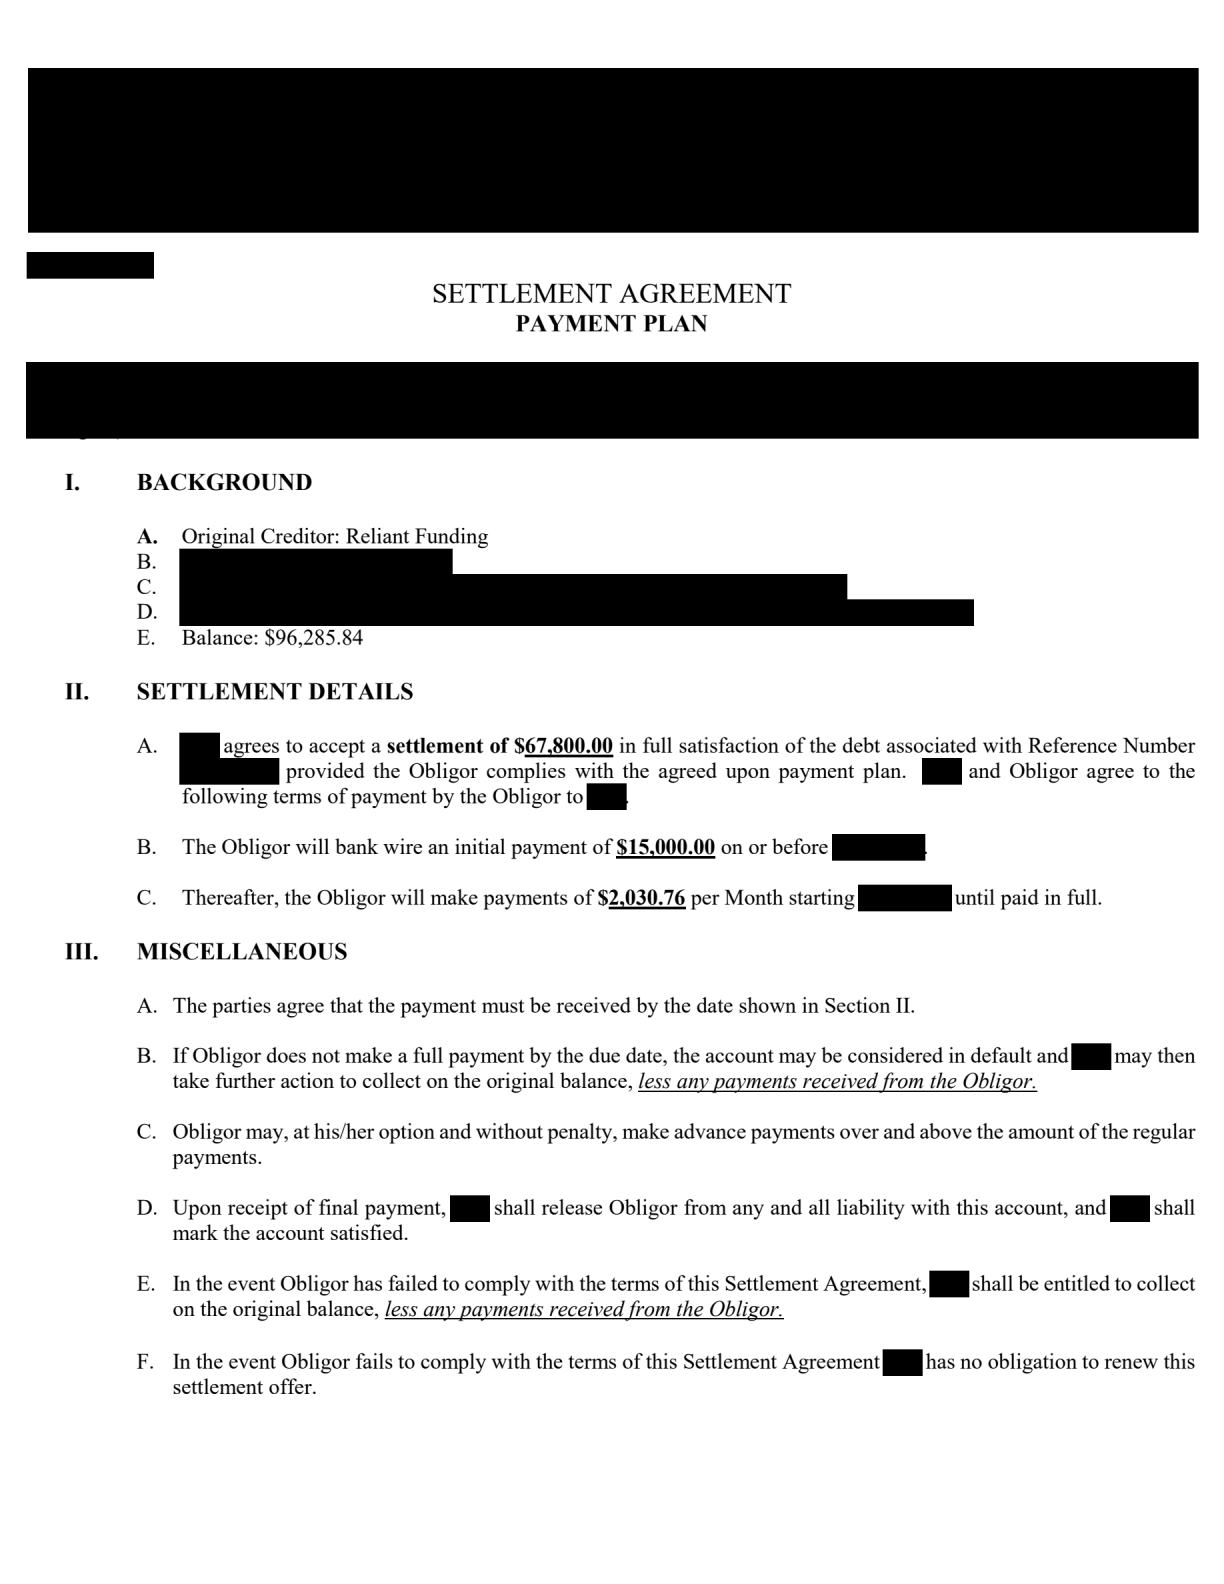
Build the cash-flow review around the entire schedule.
A manageable monthly amount can conceal an unaffordable initial payment. Set out the down payment, each due date and the source of cash for each obligation. Include other MCA commitments and any periods when customer receipts are normally slower.
Next, reconcile the schedule with the settlement total. Installment amounts can leave a different final payment or require a final accounting. Confirm that point in writing rather than calculating an assumed number of identical payments from a rounded figure.
Finally, read what happens if performance breaks down. The public Reliant example refers to the original balance, less payments received, in its default provisions. Have counsel explain the applicable terms and the release language, including which business and individual parties are covered. Keep the final release with the payment confirmations.
Where does your Reliant matter stand?
MCA payments are too much
Review both the down payment and the continuing installments against the business’s other MCA commitments.
Receivables or accounts are affected
Check whether receipts are restricted and whether any proposed plan includes instructions to address those restrictions.
Court papers have arrived
Identify the plaintiff separately from the original creditor and have counsel review the papers and any supporting transfer records.
Four practical first steps.
- Check for a court deadline.If you received court papers, identify where the case is filed and when a response is due. Settlement discussions do not automatically extend a deadline.
- Put the records in one place.Collect the agreement, payment history, bank statements, and every notice. Preserve emails and texts, including any proposed settlement terms.
- Review a proposed change before signing.A new agreement, acknowledgment, release, or guarantee can affect your rights and obligations. Have its terms reviewed in context.
- Discuss a plan for your actual situation.Ask which legal or negotiation options fit the documents, cash flow, and litigation status—and what representation would cost.
Reliant MCA questions, answered.
Why does the proposal say original creditor rather than just creditor?
It identifies a role in the account’s history. It does not by itself establish who currently owns the claim or who has authority to settle it. Match the demand and proposed release to the supporting records.
Can a lower monthly payment still be unaffordable?
Yes. Review the initial payment, other MCA obligations and cash available on the actual due dates. A proposal should be evaluated across its full schedule.
Is the final installment always the regular monthly amount?
Not necessarily. Confirm the full schedule and total, including any different final payment. Obtain the agreed terms instead of relying on a rounded calculation.
Does making the first payment release the guarantor?
Do not assume so. The agreement may condition a release on completion and may specify particular parties. Have the guarantee and settlement release reviewed together.
What does the free MCA review cover?
The initial consultation can address your MCA agreement, payment pressure, collection communications or case status. Consultations are free. Any retained legal-service fees are separate and addressed in the engagement terms.
Let’s review your Reliant MCA.
Tell us about the payment demand, proposed agreement or court papers you need help understanding.
General information, not legal advice. Options depend on the agreements, facts, applicable law, and procedural history. No result is guaranteed. Contacting the firm does not create an attorney-client relationship or extend a deadline. Business Debt Law Group provides legal services; it does not provide or arrange financing.