Wellen Capital MCA Lawsuit or Payment Pressure?
A monthly settlement schedule needs more than an acceptable total. Understand what counts as timely payment, what happens if a payment is returned and how completion will be documented.
Free MCA review or case evaluation.
No lawsuit is required to ask for help.
The Wellen file
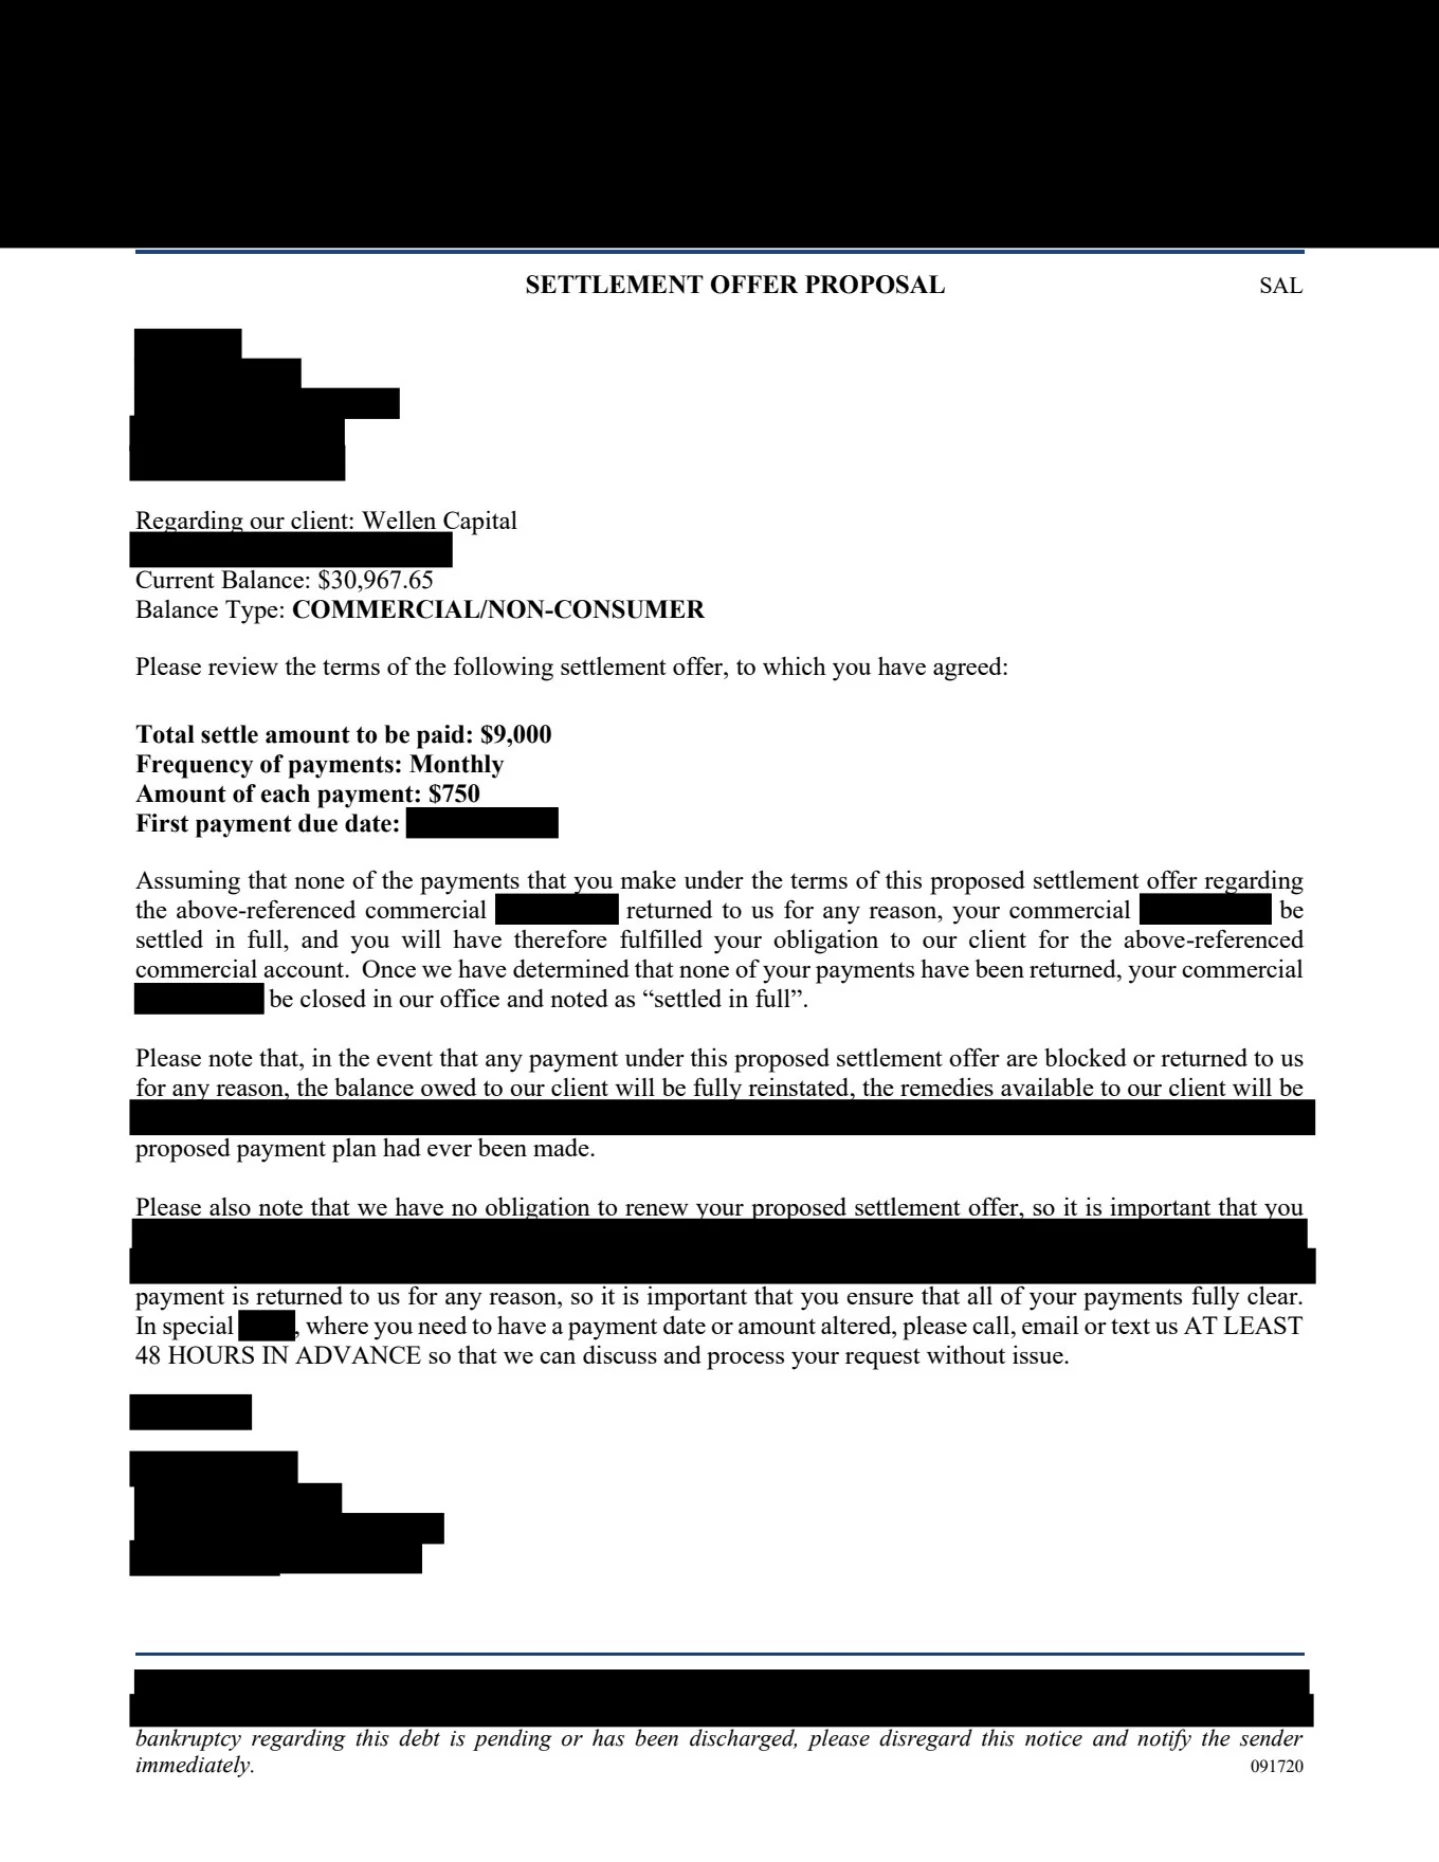
Wellen Capital is identified as the client in a settlement-offer proposal in BDLG’s published library. The excerpt provides a balance, reduced settlement total and monthly payment amount. It also includes conditions governing payment clearance and nonperformance.
The public image does not supply a complete corporate history or prove the current owner of every Wellen account. Match your own agreement, demand and sender’s authority before making assumptions about the party entitled to receive payment or release a claim.
For an owner handling multiple MCA obligations, the central question may be whether a monthly proposal can be maintained through slow periods. The example below illustrates why the default terms and account-closing conditions deserve as much attention as the reduction shown on a results card.
- Client name on the proposal
- Wellen Capital.
- Payment structure shown
- Monthly payments toward a stated settlement total.
- Distinct issue to review
- Sustaining the schedule and documenting successful completion.
- Independent legal representation
- Business Debt Law Group is not affiliated with, endorsed by, or acting for Wellen Capital.
A Wellen proposal for $750 monthly payments.
The redacted proposal lists a $30,967.65 balance, a $9,000 settlement total and $750 monthly payments. It conditions the arrangement on successful payment and describes consequences for returned or blocked payments. The excerpt is a proposal; it does not establish acceptance, completion or a release in another matter.
See more MCA settlement examples ↗
Partial, redacted excerpt from one matter. Other pages, amendments and later events may affect these terms. This discussion does not summarize the complete agreement or case. Acceptance, completed payment, releases and the final outcome require verification from the complete records. This is not a standard offer or promised result. Past results do not guarantee a similar outcome.
Test the schedule before relying on the discount.
List the proposed due dates alongside payroll, taxes, rent and other MCA obligations. A schedule that works in an average month may fail when a large customer pays late. Identify that risk during review rather than assuming the recipient will accept a different date later.
Read how the proposal treats returned payments, changes to the payment method and requests for modification. Preserve written communications, and obtain an authorized written change if new terms are agreed. A request for accommodation does not itself amend the existing terms.
At completion, reconcile payments with the agreed total and obtain written confirmation of the account’s disposition. If the original matter includes a guarantee, lawsuit, judgment or MCA UCC filing, ask what separate release or filing is required. Keep those records together so a future collection inquiry can be checked against them.
Where does your Wellen matter stand?
MCA payments are too much
Compare the monthly proposal with slower trading periods and other MCA due dates, not just average revenue.
Receivables or accounts are affected
Identify any current MCA UCC or processor restriction that affects the funds needed to maintain the proposed plan.
Court papers have arrived
Check whether a collector’s proposal addresses the existing court case, judgment and named guarantors.
Four practical first steps.
- Check for a court deadline.If you received court papers, identify where the case is filed and when a response is due. Settlement discussions do not automatically extend a deadline.
- Put the records in one place.Collect the agreement, payment history, bank statements, and every notice. Preserve emails and texts, including any proposed settlement terms.
- Review a proposed change before signing.A new agreement, acknowledgment, release, or guarantee can affect your rights and obligations. Have its terms reviewed in context.
- Discuss a plan for your actual situation.Ask which legal or negotiation options fit the documents, cash flow, and litigation status—and what representation would cost.
Wellen MCA questions, answered.
Does Wellen’s published proposal prove that my account can settle for $9,000?
No. It is one proposed arrangement concerning a specific balance. It is not a current standing offer or a prediction of another merchant’s result.
Can I move a monthly payment date if cash comes in late?
Review the agreement and request any necessary change promptly. Obtain written acceptance from an authorized party. Do not assume a unilateral change preserves the original settlement terms.
Why keep proof of each cleared payment?
It helps reconcile the account and address disputed or returned entries. A scheduled transfer and a successfully credited payment are not always the same event.
What if another MCA makes the monthly plan difficult?
Bring the other agreements and payment calendar too. The Wellen proposal must be evaluated in the context of the business’s available cash, while each funder’s rights and agreement remain separate.
What does the free MCA review cover?
The initial consultation can address your MCA agreement, payment pressure, collection communications or case status. Consultations are free. Any retained legal-service fees are separate and addressed in the engagement terms.
Let’s review your Wellen MCA.
Tell us about the payment demand, proposed agreement or court papers you need help understanding.
General information, not legal advice. Options depend on the agreements, facts, applicable law, and procedural history. No result is guaranteed. Contacting the firm does not create an attorney-client relationship or extend a deadline. Business Debt Law Group provides legal services; it does not provide or arrange financing.