Legend Advance Funding Lawsuit or a settlement default notice?
A missed Legend settlement payment raises questions about notice, timing and credited payments. Our attorneys review the original MCA and the later agreement to identify the actual issues.
Free MCA review or case evaluation.
No lawsuit is required to ask for help.
The Legend file
The excerpt in our library names Legend Advance Funding II, LLC, abbreviated LAF. The “II” is part of the entity shown, so it should not be dropped when comparing your agreement, settlement and court papers.
This example includes a personal guaranty of performance, a payment history and a written default-notice provision. Those details matter more to a review than a generalized statement that all Legend agreements work the same way.
- Legal name in the excerpt
- Legend Advance Funding II, LLC.
- Accounting shown
- $14,000 purchase price, $20,020 purchased receivables and $5,262.23 in prior payments.
- Distinct notice provision
- Five business days after receipt of a notice by email or written letter, under this document’s terms.
- Independent legal representation
- Business Debt Law Group is not affiliated with, endorsed by, or acting for Legend Advance Funding.
A Legend agreement ties the settlement to a notice-and-cure process.
The document states a $14,857.77 balance including fees and a $9,500 settlement. It lists a first monthly payment of $3,250, followed by monthly payments of $1,041.66 until paid. The prior payment history and included fees should be reconciled separately from the settlement schedule.
See more MCA settlement examples ↗
Partial, redacted excerpt from one matter. Other pages, amendments and later events may affect these terms. This discussion does not summarize the complete agreement or case. Acceptance, completed payment, releases and the final outcome require verification from the complete records. This is not a standard offer or promised result. Past results do not guarantee a similar outcome.
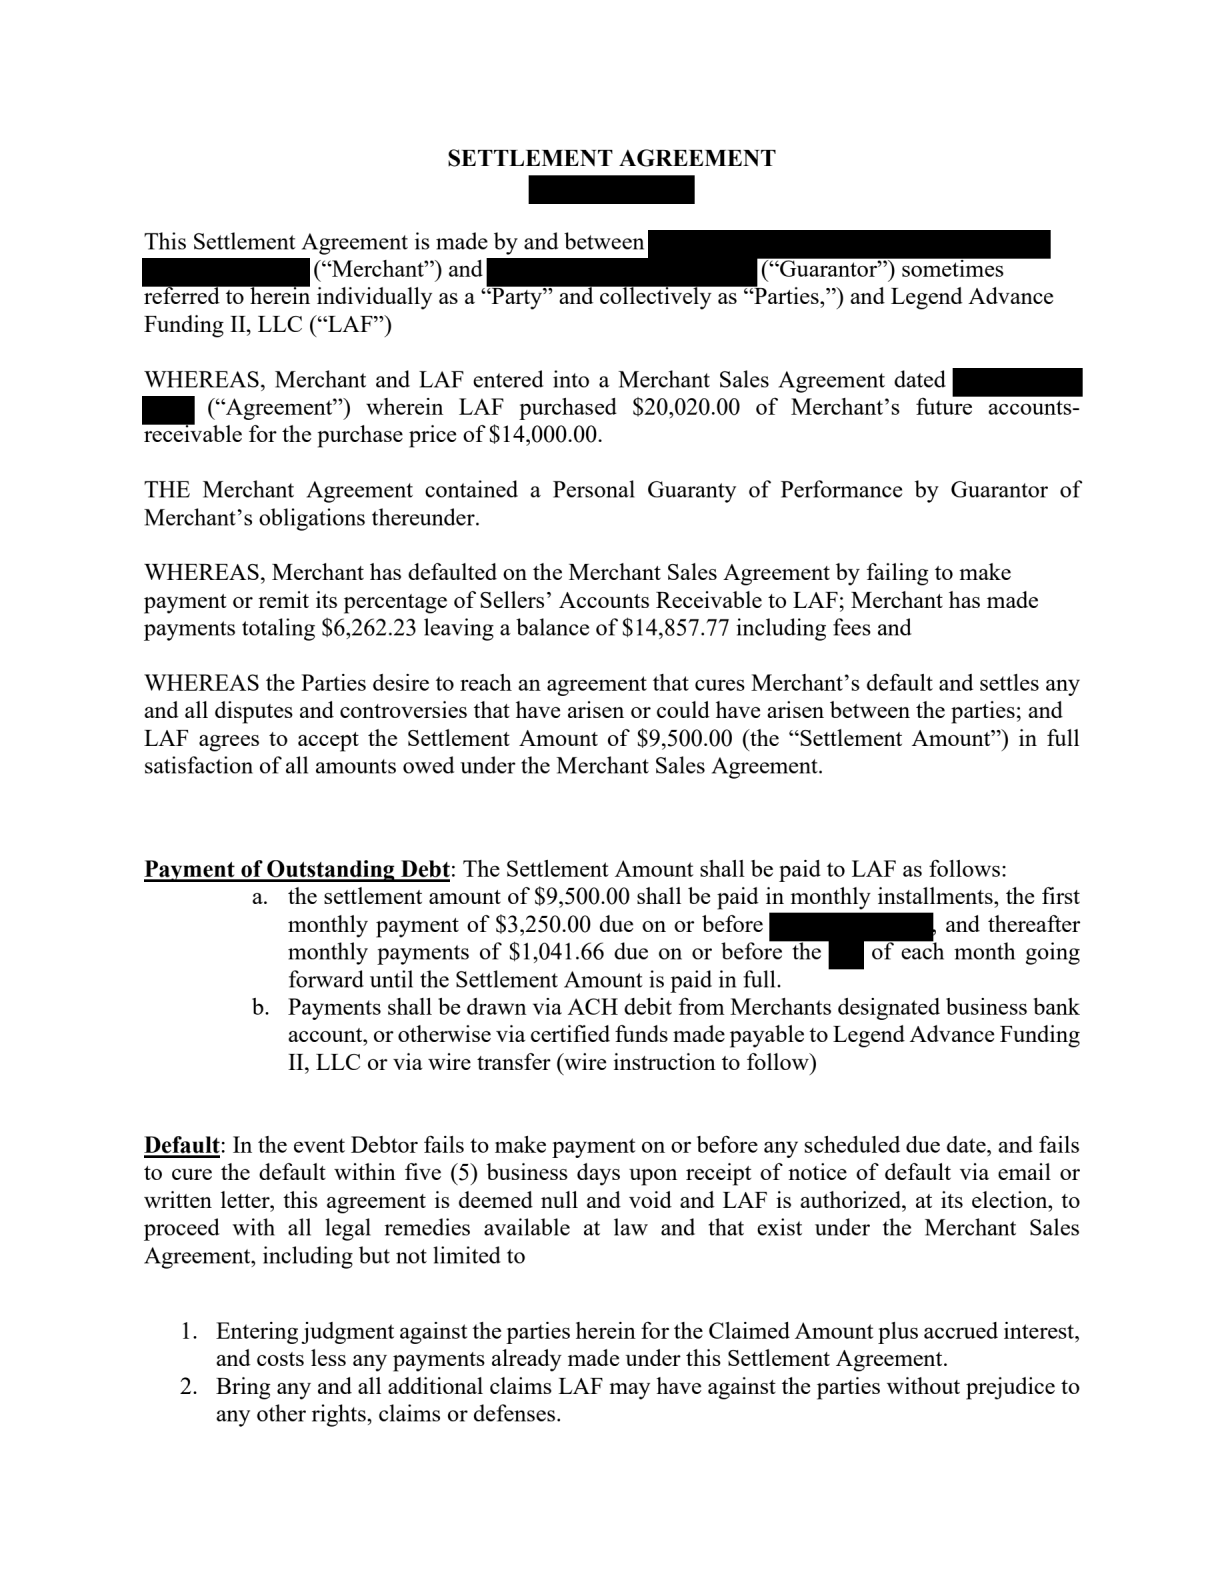
Build the timeline from the actual communication.
The visible default clause applies if a scheduled payment is missed and the default is not cured within five business days after receipt of an email or written notice. Preserve the original message, attachments and receipt information. The due date, notice date and receipt date are different facts; this clause is not a grace period for every Legend agreement.
The excerpt says that an uncured default can undo the settlement and allow pursuit of other remedies, with payments credited. Ask which claimed amount is used, how interest and costs are calculated and what procedure would be required. A contractual reference to judgment does not replace a review of the court record and applicable law.
Confirm the final installment using the complete payment schedule and current ledger. Other pages may address credits, rounding, adjustments or the last payment. The partial excerpt is not a basis to infer a shortfall or an error in the full agreement.
Where does your Legend matter stand?
MCA payments are too much
Compare the remaining settlement installments with current receipts and raise performance difficulties before a due date is missed.
Receivables or accounts are affected
Preserve any notices affecting receipts and ask what release steps follow completed performance.
Court papers have arrived
Provide any settlement default notice immediately, along with the case papers and proof of receipt.
Four practical first steps.
- Check for a court deadline.If you received court papers, identify where the case is filed and when a response is due. Settlement discussions do not automatically extend a deadline.
- Put the records in one place.Collect the agreement, payment history, bank statements, and every notice. Preserve emails and texts, including any proposed settlement terms.
- Review a proposed change before signing.A new agreement, acknowledgment, release, or guarantee can affect your rights and obligations. Have its terms reviewed in context.
- Discuss a plan for your actual situation.Ask which legal or negotiation options fit the documents, cash flow, and litigation status—and what representation would cost.
Legend MCA questions, answered.
Does the five-business-day period start on the payment date?
The visible clause ties its cure period to receipt of a default notice. Your full agreement and actual communications must be reviewed; do not calculate a deadline from this public example alone.
Is Legend Advance Funding II the name I should look for?
That is the entity named in this document. Use the exact name in your own records and verify any difference rather than assuming related names are interchangeable.
Why ask for a final payment figure if monthly amounts are listed?
Other pages and the account ledger may address the final installment, credits or adjustments. Confirm the final amount and closing documents from those records rather than reconstructing the whole plan from an excerpt.
Does a settlement default erase payments already made?
The example refers to crediting payments when discussing further remedies. Confirm the complete ledger and the language governing your matter before accepting a new demand.
What does the free MCA review cover?
The initial consultation can address your MCA agreement, payment pressure, collection communications or case status. Consultations are free. Any retained legal-service fees are separate and addressed in the engagement terms.
Let’s review your Legend MCA.
Tell us about the payment demand, proposed agreement or court papers you need help understanding.
General information, not legal advice. Options depend on the agreements, facts, applicable law, and procedural history. No result is guaranteed. Contacting the firm does not create an attorney-client relationship or extend a deadline. Business Debt Law Group provides legal services; it does not provide or arrange financing.