Capital Assist MCA lawsuit or a settlement with a wire deadline?
A Capital Assist settlement may require more than agreeing on a total. Review who must receive the money, when it must arrive and which collection notices are released after the first payment.
Free MCA review or case evaluation.
No lawsuit is required to ask for help.
The Capital Assist file
Capital Assist’s website describes merchant cash advances and an ISO partner program. Your original contact may therefore be different from the party authorized to change the account or settle a filed case. Identify the funder, any broker and the attorney handling the lawsuit from your documents.
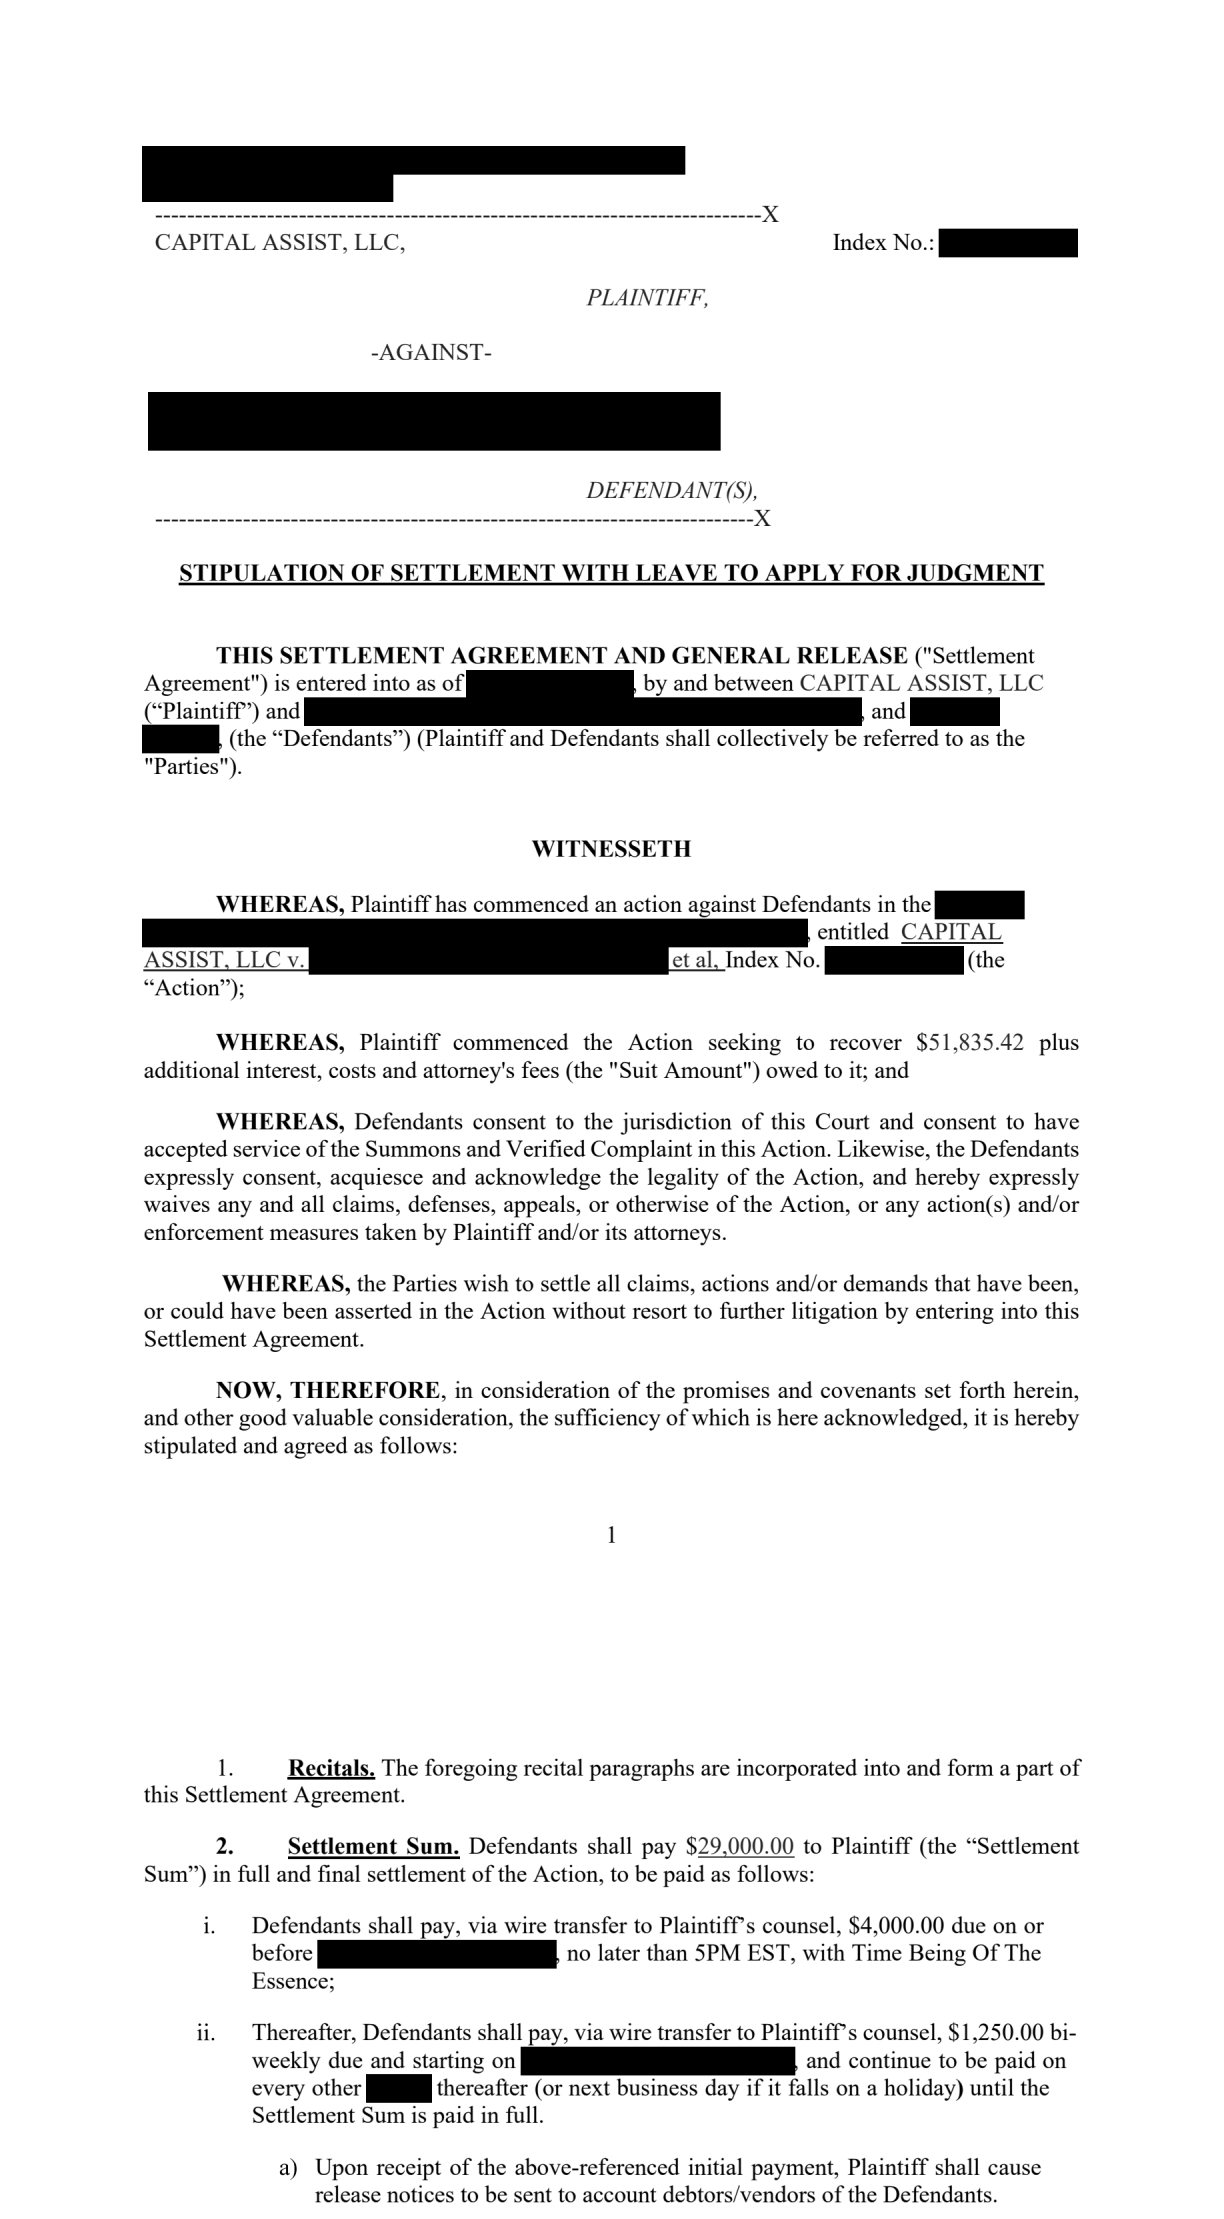
BDLG’s public excerpt names Capital Assist, LLC as plaintiff. It is headed as a settlement stipulation with leave to apply for judgment and contains terms about consent to jurisdiction, service and defenses. Those provisions deserve review alongside the payment schedule.
The distinctive issue in this example is operational: the initial wire, the later biweekly wires and the release notices have a stated sequence. A business needs both workable terms and a reliable way to document that each condition was met.
- Named plaintiff
- Capital Assist, LLC
- Method shown in the excerpt
- Wire payments to plaintiff’s counsel
- Collection milestone
- Release notices after receipt of the initial payment
- Independent legal representation
- Business Debt Law Group is not affiliated with, endorsed by, or acting for Capital Assist.
An initial wire followed by biweekly payments
The excerpt states a $51,835.42 suit amount plus interest, costs and attorneys’ fees. It describes $29,000 settlement terms: an initial $4,000 wire by a specified date and time, followed by $1,250 biweekly wires. It addresses a holiday adjustment for later payments and says release notices to account debtors or vendors follow receipt of the initial payment. This does not show that the payments or releases occurred.
See more MCA settlement examples ↗
Partial, redacted excerpt from one matter. Other pages, amendments and later events may affect these terms. This discussion does not summarize the complete agreement or case. Acceptance, completed payment, releases and the final outcome require verification from the complete records. This is not a standard offer or promised result. Past results do not guarantee a similar outcome.
Make the payment and release sequence explicit
A wire initiated before a deadline may arrive later. Read whether the agreement requires sending or receipt, the time zone and any holiday rule. Verify payment instructions through a trusted contact before transmitting funds, and keep the receipt and written acknowledgment with the settlement ledger.
List every account debtor or vendor that received a collection notice. If releases are due after the initial payment, confirm which recipients are covered, who sends the instructions and what evidence shows delivery. Ask about any remaining bank or processor restriction separately; one release may not address every hold.
The title’s reference to applying for judgment and the text concerning consent or waivers make the omitted pages important. Obtain the complete stipulation before assessing notice, cure, default remedies and final releases. Do not assume a lower settlement total preserves every defense from the original lawsuit.
Where does your Capital Assist matter stand?
MCA payments are too much
Assess whether the initial wire and recurring installments fit the business’s available cash on their actual due dates.
Receivables or accounts are affected
Collect the original notices and create a recipient list so each promised release can be checked.
Court papers have arrived
Review the stipulation’s judgment provisions and the pending case before signing or missing a response deadline.
Four practical first steps.
- Check for a court deadline.If you received court papers, identify where the case is filed and when a response is due. Settlement discussions do not automatically extend a deadline.
- Put the records in one place.Collect the agreement, payment history, bank statements, and every notice. Preserve emails and texts, including any proposed settlement terms.
- Review a proposed change before signing.A new agreement, acknowledgment, release, or guarantee can affect your rights and obligations. Have its terms reviewed in context.
- Discuss a plan for your actual situation.Ask which legal or negotiation options fit the documents, cash flow, and litigation status—and what representation would cost.
Capital Assist MCA questions, answered.
Is sending a wire the same as meeting a receipt deadline?
Not necessarily. Read the exact requirement and allow for processing. Keep proof of receipt or written acknowledgment where the agreement requires it.
Does the example promise every restriction is lifted?
The visible provision addresses release notices to account debtors or vendors after the initial payment. It does not establish the removal of every possible restriction.
Can my broker approve a settlement in a filed case?
Do not assume so. Confirm the authority of the funder or counsel giving the approval and obtain the complete written terms.
Why do the later pages matter if the amount is clear?
They may address default, notice, cure, judgment, waivers and releases. Those conditions can materially affect how the stated payment terms operate.
What does the free MCA review cover?
The initial consultation can address your MCA agreement, payment pressure, collection communications or case status. Consultations are free. Any retained legal-service fees are separate and addressed in the engagement terms.
Let’s review your Capital Assist MCA.
Tell us about the payment demand, proposed agreement or court papers you need help understanding.
General information, not legal advice. Options depend on the agreements, facts, applicable law, and procedural history. No result is guaranteed. Contacting the firm does not create an attorney-client relationship or extend a deadline. Business Debt Law Group provides legal services; it does not provide or arrange financing.