Wise Funding MCA payment dispute after substantial amounts were already paid?
The advance, purchased amount, credited payments and claimed balance are different figures. Reconcile them before evaluating a new demand or settlement.
Free MCA review or case evaluation.
No lawsuit is required to ask for help.
The Wise Funding file
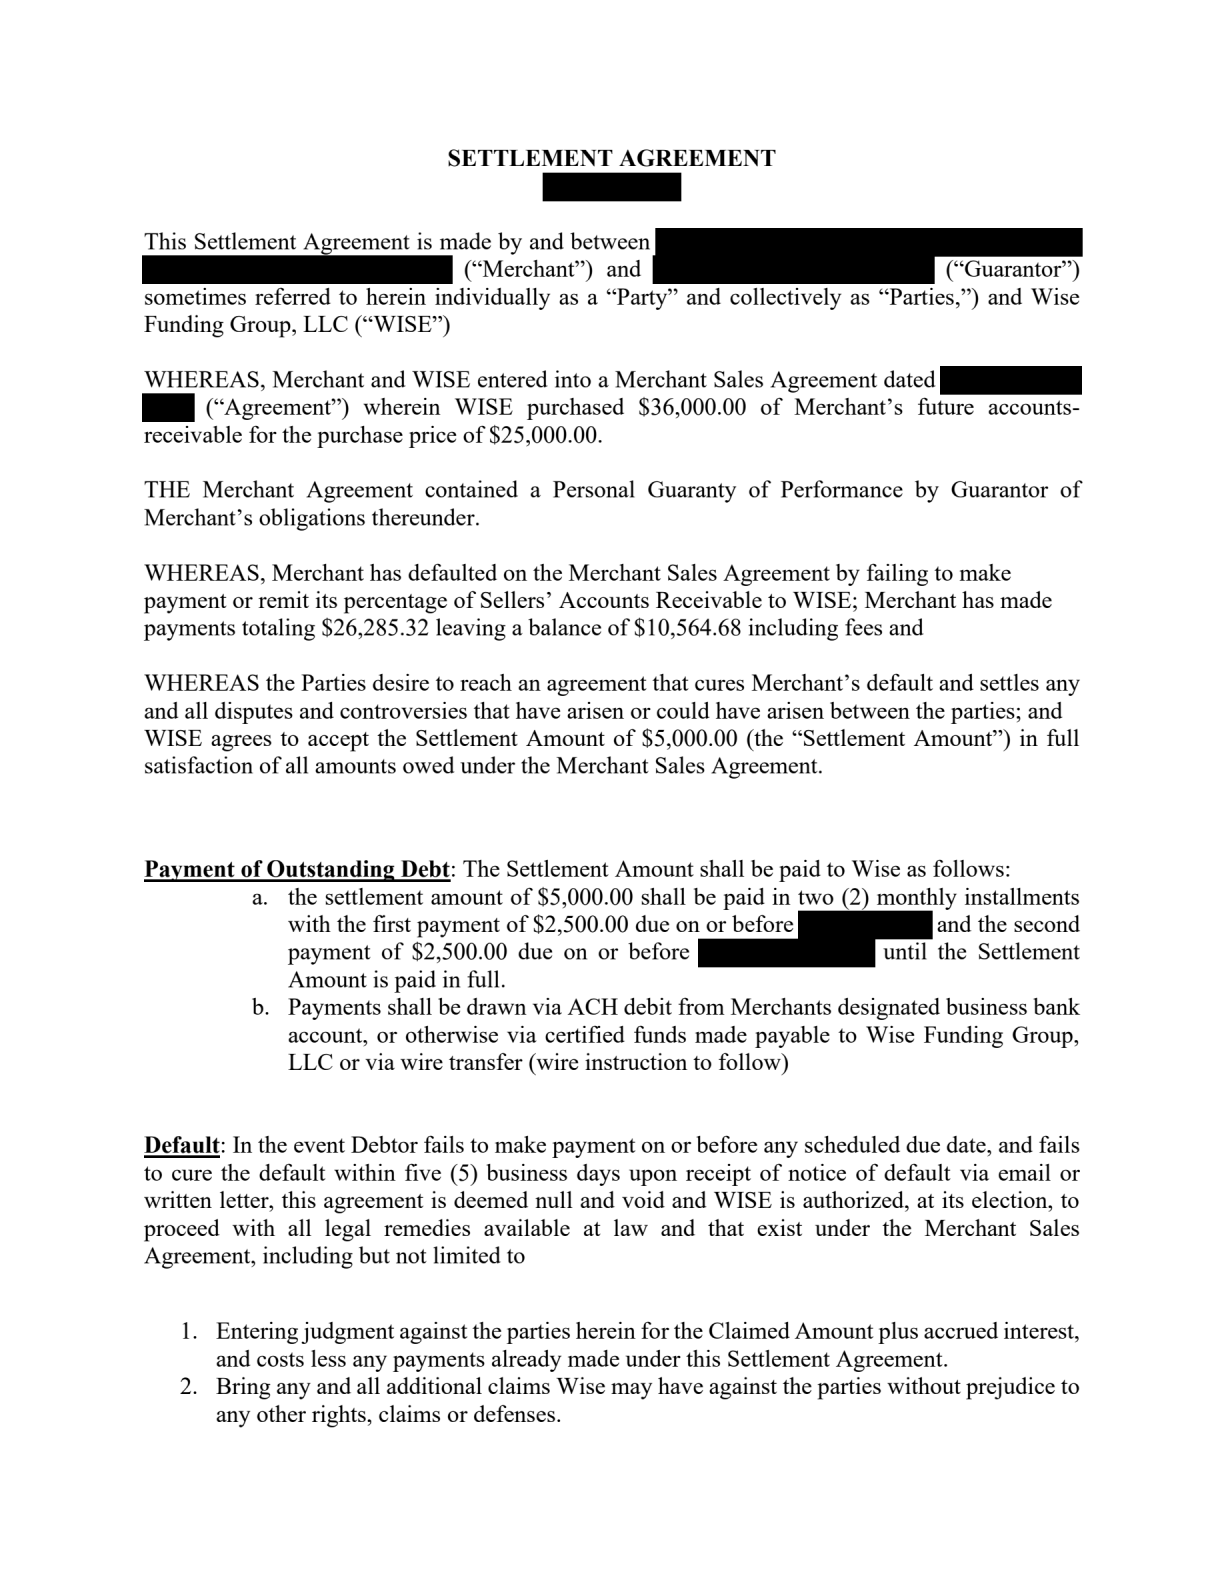
The redacted agreement names Wise Funding Group, LLC and describes a Merchant Sales Agreement with a personal guaranty of performance. It recites a $25,000 purchase price for $36,000 in future receivables.
It states that $26,285.32 had been paid and gives a $10,564.68 balance including fees. Those figures illustrate why comparing total payments only with the cash originally received does not explain the entire claimed account balance.
This guide concerns that specific MCA counterparty and document. It does not identify the international Wise payments service or other similarly named funding businesses as the same company.
- Entity in the excerpt
- Wise Funding Group, LLC
- Original figures recited
- $25,000 purchase price / $36,000 purchased receivables
- Settlement schedule shown
- Two monthly payments of $2,500
- Independent legal representation
- Business Debt Law Group is not affiliated with, endorsed by, or acting for Wise Funding.
A $5,000 settlement proposal after prior payments
The excerpt states $26,285.32 in previous payments, a $10,564.68 balance including fees and $5,000 settlement terms in two monthly $2,500 installments. It discusses ACH, certified funds or wire payment and a five-business-day cure period after receipt of an emailed or written default notice. These are the terms visible in one partial record, not verified performance or a standing Wise offer.
See more MCA settlement examples ↗
Partial, redacted excerpt from one matter. Other pages, amendments and later events may affect these terms. This discussion does not summarize the complete agreement or case. Acceptance, completed payment, releases and the final outcome require verification from the complete records. This is not a standard offer or promised result. Past results do not guarantee a similar outcome.
Ask for the calculation behind the balance
Arrange the figures in sequence: funded cash, purchased receivables, credited payments, added fees and the current demand. Request an itemized ledger explaining differences. The fact that payments exceed the original purchase price does not, on its own, establish either full satisfaction or the validity of every remaining charge.
If settling, agree on the payment method and keep it consistent with the authorization. Where the document allows ACH or another method, clarify what happens to an automatic debit when a wire or certified payment is sent. Preserve instructions and credits to avoid counting or collecting the same installment twice.
Review the default notice and cure language in full. This excerpt says five business days after receipt of notice, which differs from clauses measured from the due date or in calendar days. Keep the original notice and payment records; do not use this example to calculate a deadline under another agreement.
Where does your Wise Funding matter stand?
MCA payments are too much
Reconcile prior payments and fees before deciding whether the claimed remaining balance is accurate.
Receivables or accounts are affected
Compare collection demands with the ledger and preserve evidence of any duplicate or uncredited payment.
Court papers have arrived
Review the guaranty, notice and court papers together; the settlement’s cure period does not itself extend a court deadline.
Four practical first steps.
- Check for a court deadline.If you received court papers, identify where the case is filed and when a response is due. Settlement discussions do not automatically extend a deadline.
- Put the records in one place.Collect the agreement, payment history, bank statements, and every notice. Preserve emails and texts, including any proposed settlement terms.
- Review a proposed change before signing.A new agreement, acknowledgment, release, or guarantee can affect your rights and obligations. Have its terms reviewed in context.
- Discuss a plan for your actual situation.Ask which legal or negotiation options fit the documents, cash flow, and litigation status—and what representation would cost.
Wise Funding MCA questions, answered.
Does paying more than the original advance mean the account is paid off?
Not necessarily. The purchased amount, credited payments, fees and applicable contract terms must be reviewed. That does not mean every claimed charge is valid.
Are the five cure days business days in this excerpt?
Yes, the visible provision says business days after receipt of an emailed or written notice. Use the complete agreement for an actual deadline review.
Can I wire a payment while ACH is active?
Clarify the authorized method and handling of any scheduled debit first, and retain written instructions and receipts.
Is this about the Wise money-transfer service?
No. This guide addresses the Wise Funding Group, LLC MCA record identified in the excerpt.
What does the free MCA review cover?
The initial consultation can address your MCA agreement, payment pressure, collection communications or case status. Consultations are free. Any retained legal-service fees are separate and addressed in the engagement terms.
Let’s review your Wise Funding MCA.
Tell us about the payment demand, proposed agreement or court papers you need help understanding.
General information, not legal advice. Options depend on the agreements, facts, applicable law, and procedural history. No result is guaranteed. Contacting the firm does not create an attorney-client relationship or extend a deadline. Business Debt Law Group provides legal services; it does not provide or arrange financing.