Fundbox Lawsuit or payment pressure? Start with the product.
A Fundbox account can sit alongside several MCAs in the same business. Before treating every withdrawal as part of the same problem, identify the agreement, the funding provider and the payment schedule for each account.
Free MCA review or case evaluation.
No lawsuit is required to ask for help.
The Fundbox file
Fundbox's current platform website lists revenue-based financing alongside lines of credit, term loans and invoice financing. Its lending disclosures also identify bank-originated loans and credit lines. A Fundbox-branded account should not automatically be called an MCA.
This matters when a business is juggling Fundbox payments and separate merchant cash advances. BDLG's focus is MCA matters. The review should identify which obligations are MCAs and how the other withdrawals affect the business's ability to address them, without promising that MCA contract provisions apply to a different product.
- Product range
- The current Fundbox platform site lists multiple products, including revenue-based financing and credit lines.
- Distinct review issue
- Separating each agreement and payment schedule when financing is delivered through a platform or involves several draws.
- Settlement classification
- The example below remains labeled business financing; its underlying product is not established by the excerpt.
- Independent legal representation
- Business Debt Law Group is not affiliated with, endorsed by, or acting for Fundbox.
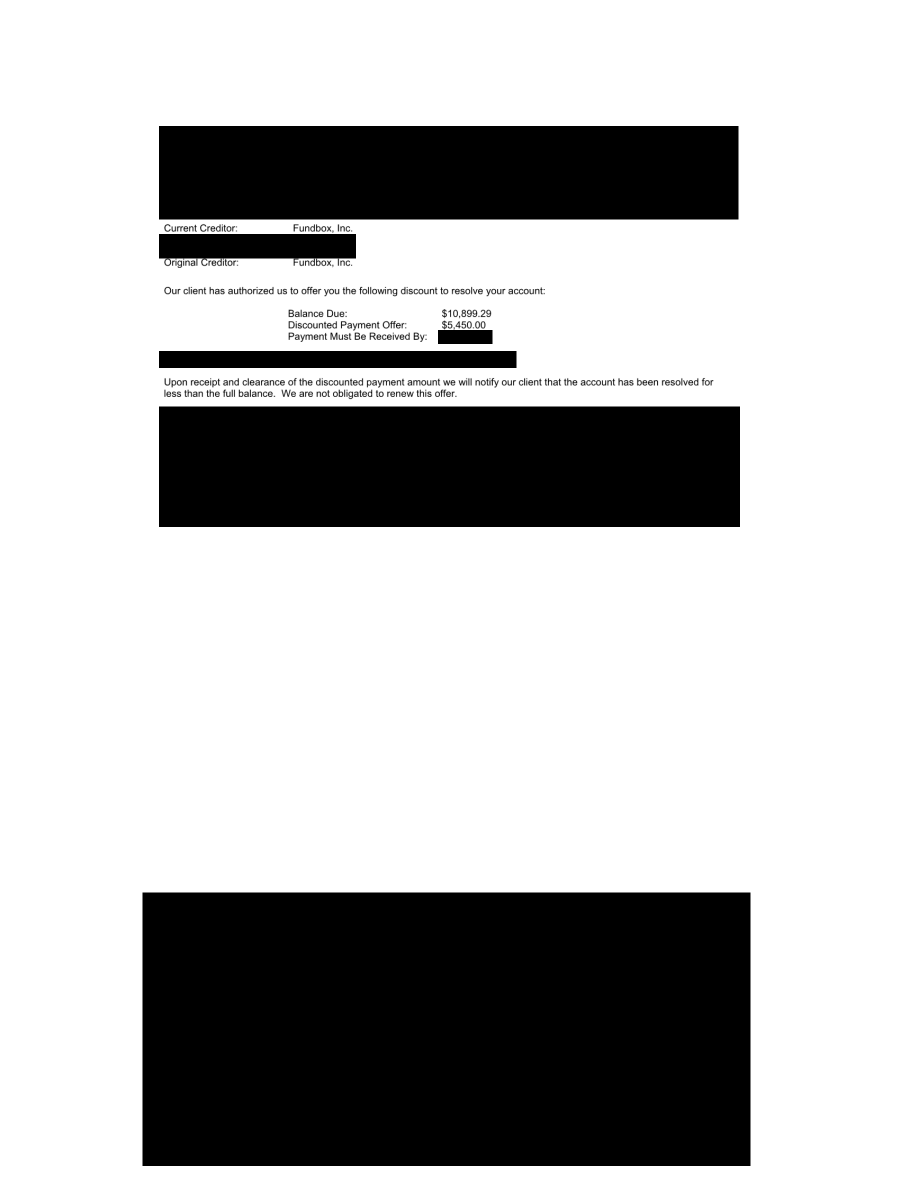
A Fundbox offer with a limited documentary record
The public excerpt shows a $10,899.29 comparison amount and proposed terms of $5,450. Acceptance and payment completion are not established. We do not label this particular transaction an MCA based on the company name or on its current product offerings.
See more documented settlement examples ↗
Partial, redacted excerpt from one matter. Other pages, amendments and later events may affect these terms. This discussion does not summarize the complete agreement or case. Acceptance, completed payment, releases and the final outcome require verification from the complete records. This is not a standard offer or promised result. Past results do not guarantee a similar outcome.
Separate the accounts before comparing your options.
Download the executed documents rather than relying only on the name displayed in an app or a bank-statement description. Record the legal entity providing the funding, the agreement date, the account or draw identifier and whether the document describes a loan, credit line or purchase of receivables.
Where the records show separate draws, map each draw's deposit, scheduled payments and outstanding amount. Compare that schedule with each MCA withdrawal on the same bank account. This makes it easier to see which obligation changed, which payment was missed and whether a demand includes more than one agreement.
A revenue-linked collection method does not by itself settle the legal classification. Likewise, a reconciliation provision from an unrelated MCA should not be assumed to apply to a Fundbox credit line. The contract, transaction facts and applicable law need to be evaluated together.
If a Fundbox lawsuit arrives while you are negotiating your MCAs, keep those matters separate in your records. Identify the plaintiff and agreement in the complaint, preserve the service details, and obtain advice about the actual response requirements. A resolution with another funder does not automatically dispose of the Fundbox claim.
Where does your Fundbox matter stand?
MCA payments are too much
Map Fundbox withdrawals alongside your MCAs. A clear schedule helps distinguish the cash-flow problem from the terms of each individual agreement.
Receivables or accounts are affected
Identify which party sent the notice and the account it covers. Do not assume a notice about one financing agreement applies to every receivable.
Court papers have arrived
Read the named plaintiff, account and attached contract. Tell counsel which other MCA claims or negotiations are happening at the same time.
Four practical first steps.
- Check for a court deadline.If you received court papers, identify where the case is filed and when a response is due. Settlement discussions do not automatically extend a deadline.
- Put the records in one place.Collect the agreement, payment history, bank statements, and every notice. Preserve emails and texts, including any proposed settlement terms.
- Review a proposed change before signing.A new agreement, acknowledgment, release, or guarantee can affect your rights and obligations. Have its terms reviewed in context.
- Discuss a plan for your actual situation.Ask which legal or negotiation options fit the documents, cash flow, and litigation status—and what representation would cost.
Fundbox: questions about MCA matters.
Is Fundbox a merchant cash advance company?
Its current platform product suite includes revenue-based financing as well as loans, credit lines and other financing. That does not mean every Fundbox account is an MCA. Review the particular agreement and originating entity.
Can I use an MCA reconciliation clause to change a Fundbox credit-line payment?
Do not assume so. A provision in a separate MCA agreement does not automatically govern a credit line. The specific product documents and available options must be reviewed.
Why include Fundbox when BDLG focuses on MCAs?
Businesses sometimes have both Fundbox financing and MCAs, and Fundbox's current platform offering includes revenue-based financing. This guide helps owners distinguish those obligations rather than presenting all business financing as an MCA.
What does the free MCA review cover?
The initial consultation can address your MCA agreement, payment pressure, collection communications or case status. Consultations are free. Any retained legal-service fees are separate and addressed in the engagement terms.
Let’s review the MCA issues affecting your business.
Tell us about the payment demand, proposed agreement or court papers you need help understanding.
General information, not legal advice. Options depend on the agreements, facts, applicable law, and procedural history. No result is guaranteed. Contacting the firm does not create an attorney-client relationship or extend a deadline. Business Debt Law Group provides legal services; it does not provide or arrange financing.