Rapid Finance Lawsuit or MCA payment problems?
Facing a Rapid Finance lawsuit or unaffordable MCA payments? Our attorneys help business owners review merchant cash advance and business-loan agreements, payment demands and proposed settlement terms.
Free initial case review.
No lawsuit is required to ask for help.
The Rapid file
Rapid's public financing information includes business loans and merchant cash advances. Its site also identifies Small Business Financial Solutions, LLC and Rapid Financial Services, LLC in its product disclosures. The agreement, any assignment and the party making the demand should be matched before evaluating options.
The supplied settlement document names Small Business Financial Solutions, LLC as Rapid Finance and expressly refers to a Business Loan and Security Agreement. This particular example is therefore presented as business-loan documentation, not an MCA settlement. That distinction does not determine the product in another Rapid customer's file.
Public sources: Rapid Finance financing options · Rapid Finance entity disclosures
- Entity in this document
- Small Business Financial Solutions, LLC (Rapid Finance).
- Underlying contract
- Expressly described as a Business Loan and Security Agreement.
- Review priority
- Two alternative payment options and the separate default and confessed-judgment provisions.
- Independent legal representation
- Business Debt Law Group is not affiliated with, endorsed by, or acting for Rapid Finance.
Two alternatives: weekly installments or a dated lump sum.
The document states a remaining balance of $112,430.75 and provides two alternatives: pay that amount in $1,500 weekly installments, or pay $93,590.75 as a lump sum by September 30, 2024. The dated lump-sum option is not a current offer.
The supplied copy contains customer signatures but no lender signature in its signature block. It does not establish which option was selected, whether the terms became effective or whether payments were completed. We do not describe the lower option as realized savings.
View more documented settlement examples ↗
Partial, redacted excerpt from one matter. Other pages, amendments and later events may affect these terms. This is not a complete agreement or case history. The excerpt does not establish acceptance, completed payments, releases or a final case outcome. Past results do not guarantee a similar outcome.
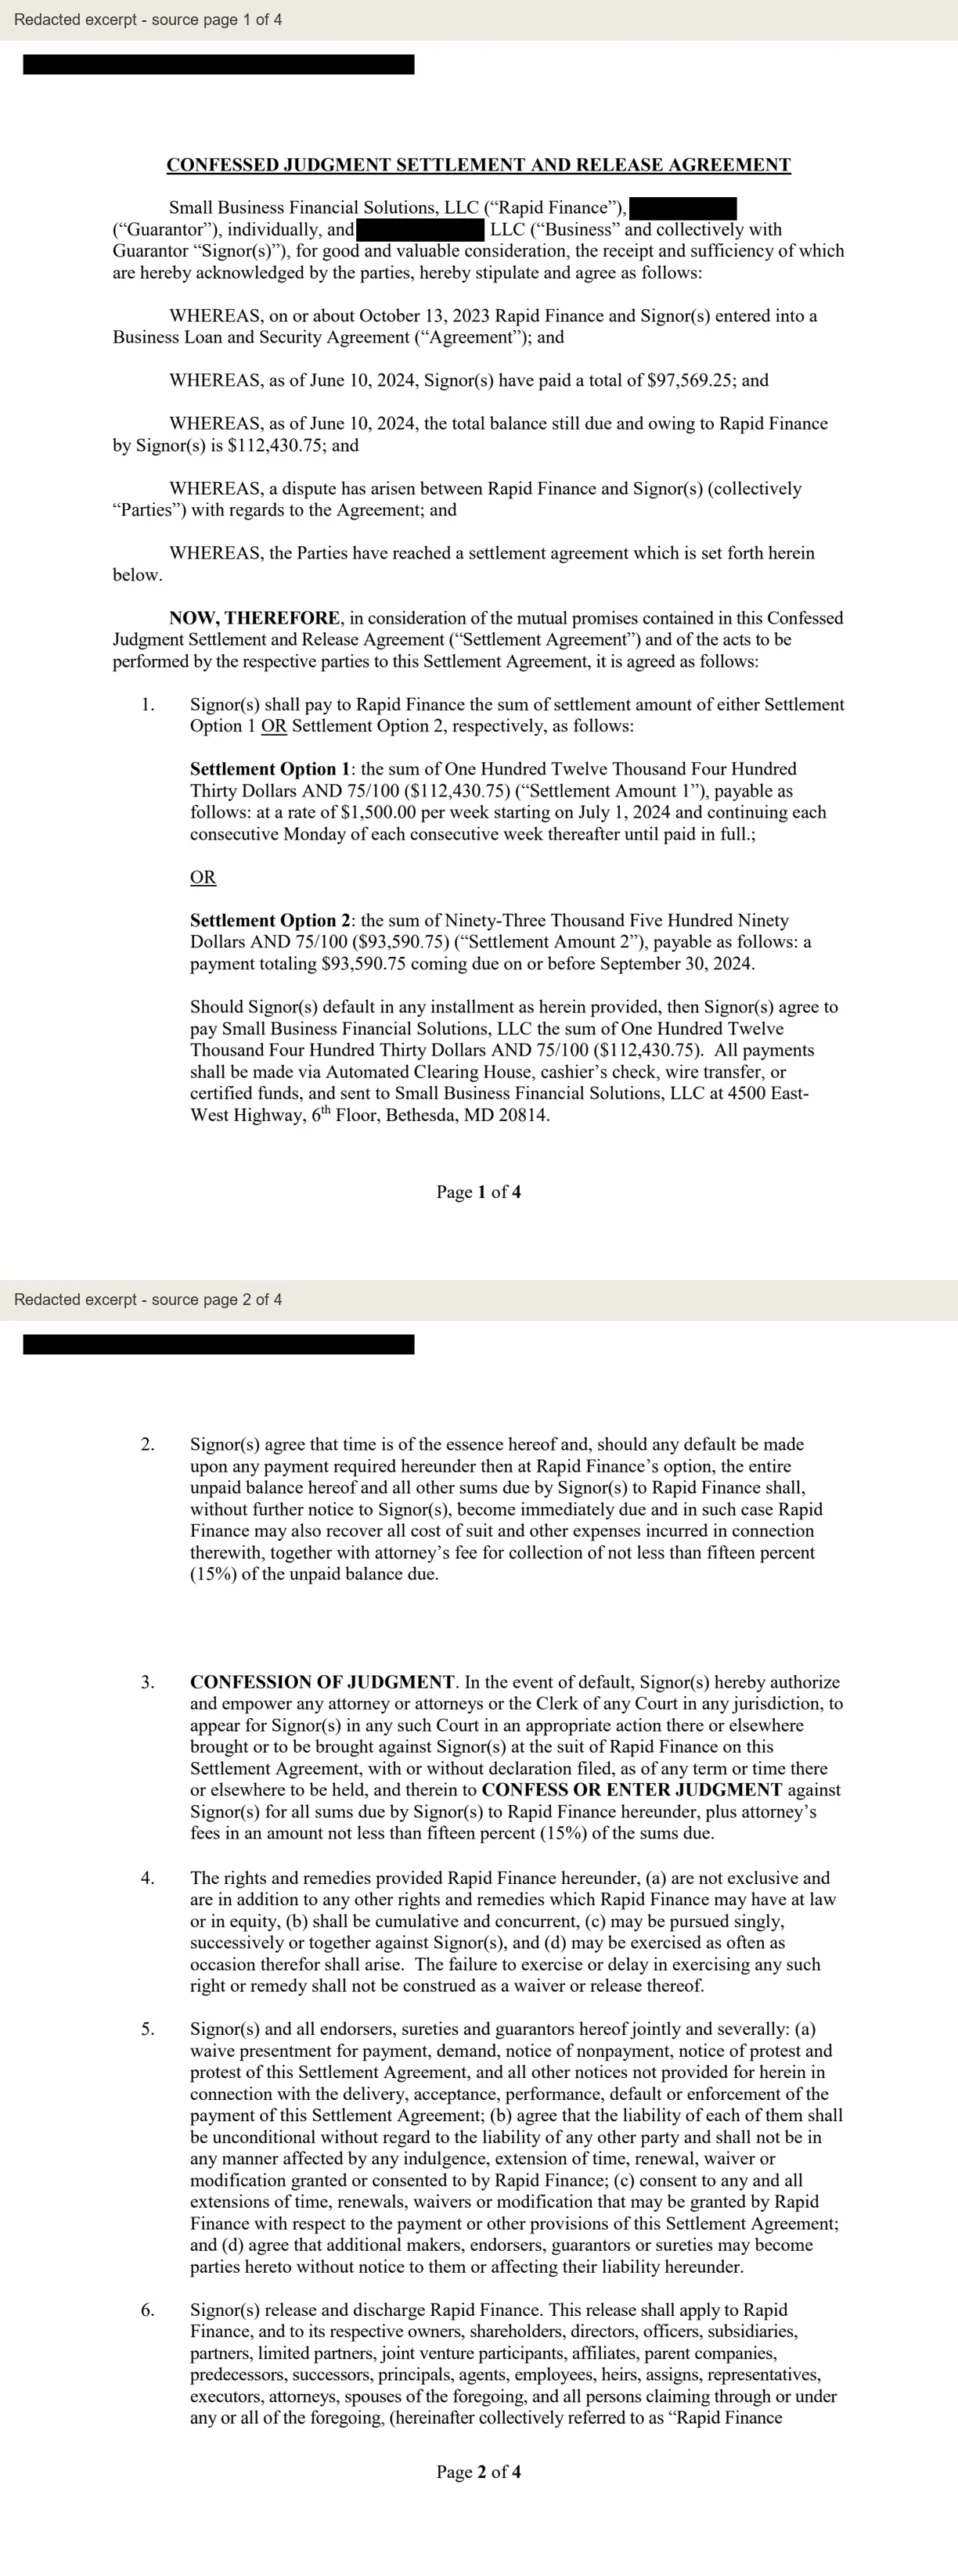
A lower total may come with a very different deadline and risk.
Comparing settlement totals alone leaves out the funding needed to meet the schedule. In this example, one option spreads payments weekly while the other requires a lump sum by a fixed date. A business needs to evaluate both the total and its ability to meet the actual written conditions.
The document also contains acceleration, collection-cost and confessed-judgment language. These provisions warrant review before signing, especially alongside guarantees, waivers and releases. Their legal effect depends on the agreement, applicable law and procedure; the document's wording does not itself prove that a judgment was entered or could be enforced in every jurisdiction.
The agreement references Maryland law, which is not proof that a particular lawsuit was filed there. Bring any actual court papers so the court, deadline, service history and relief requested can be assessed independently of the contract's choice-of-law clause.
Four practical first steps.
- Check for a court deadline.If you received court papers, identify where the case is filed and when a response is due. Settlement discussions do not automatically extend a deadline.
- Put the records in one place.Collect the agreement, payment history, bank statements, and every notice. Preserve emails and texts, including any proposed settlement terms.
- Review a proposed change before signing.A new agreement, acknowledgment, release, or guarantee can affect your rights and obligations. Have its terms reviewed in context.
- Discuss a plan for your actual situation.Ask which legal or negotiation options fit the documents, cash flow, and litigation status—and what representation would cost.
Rapid questions, answered.
Is Rapid Finance always an MCA provider?
Rapid's public product information includes both loans and MCAs. This example specifically identifies a business loan. Your own signed agreement must be reviewed to identify the relevant product and obligations.
Did this business necessarily pay the lower lump-sum amount?
The supplied document does not establish that. It describes alternative terms, including a dated lump-sum option. Selection, acceptance and performance need separate evidence.
What does the confessed-judgment language mean for my review?
It is a provision for an attorney to evaluate with the full agreement, applicable law and procedural record. Do not assume the clause is automatically enforceable or automatically invalid, or that a court judgment already exists.
Can BDLG help with a Rapid business loan dispute rather than an MCA?
You can request a case evaluation. The firm will review the type of obligation, dispute and jurisdiction to determine whether representation is appropriate.
What does the free case review cover?
The initial consultation can address your funding agreement, payment pressure, collection communications or case status. Any retained legal-service fees are separate and addressed in the engagement terms.
Let’s review your Rapid matter.
Tell us about the payment demand, proposed agreement or court papers you need help understanding.
General information, not legal advice. Options depend on the agreements, facts, applicable law, and procedural history. No result is guaranteed. Contacting the firm does not create an attorney-client relationship or extend a deadline. Business Debt Law Group provides legal services; it does not provide or arrange financing.