Credibly Lawsuit or an MCA settlement proposal?
A proposed payment plan is only part of a Credibly dispute. Our attorneys help business owners review who is making the claim, what the agreement requires and what would happen if a proposed settlement payment is missed.
Free initial case review.
No lawsuit is required to ask for help.
The Credibly file
Credibly offers merchant cash advances and other business-financing products. Its public disclosures distinguish Retail Capital LLC from Credibly or Arizona LLC depending on the product and jurisdiction. Use the legal name on your own agreement and court papers rather than assuming every Credibly account has the same creditor.
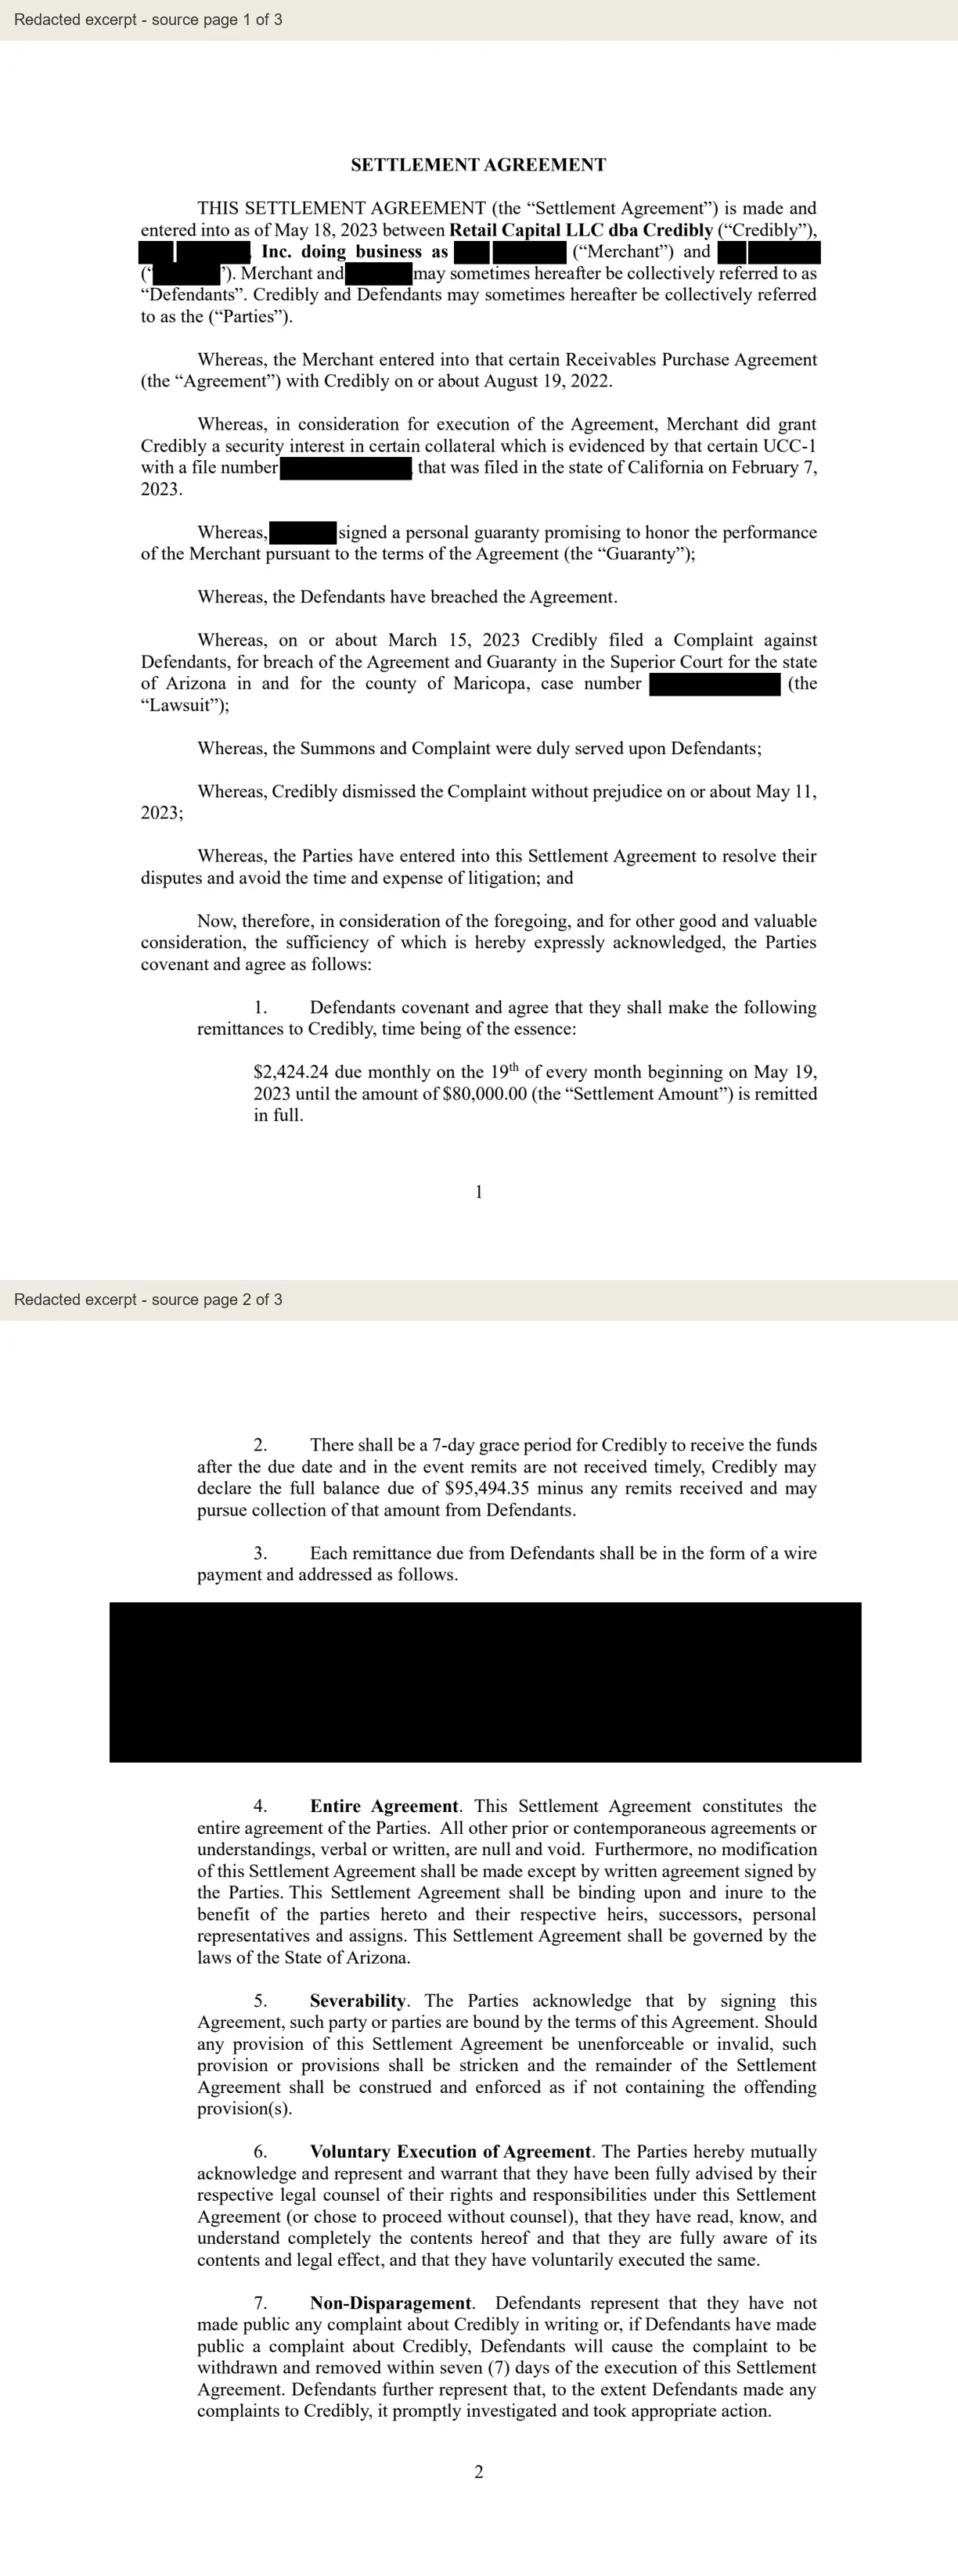
The redacted proposal below names Retail Capital LLC doing business as Credibly and identifies an underlying receivables purchase agreement. It also recites an Arizona lawsuit and a California UCC filing. Those statements describe this document; they do not establish where every Credibly case is filed or prove the present status of any case.
Public sources: Credibly MCA information and entity disclosures
- Name in this proposal
- Retail Capital LLC dba Credibly.
- Type of source
- Unsigned proposed settlement terms relating to a receivables purchase agreement.
- Important distinction
- A proposed payment schedule is not proof of acceptance, completed payment or final case closure.
- Independent legal representation
- Business Debt Law Group is not affiliated with, endorsed by, or acting for Credibly.
Proposed $80,000 payment plan with a separate default provision.
The supplied proposal calls for monthly remittances of $2,424.24 until a total of $80,000 is paid. It provides a seven-day grace period and states that, after a payment default, Credibly may declare $95,494.35 due, less remittances received.
The copy supplied has blank signature lines. It is displayed as proposed terms, not a completed or fully executed settlement. Its recitals describe a dismissal without prejudice, but the current court record and any later agreement would need to be checked separately.
View more documented settlement examples ↗
Partial, redacted excerpt from one matter. Other pages, amendments and later events may affect these terms. This is not a complete agreement or case history. The excerpt does not establish acceptance, completed payments, releases or a final case outcome. Past results do not guarantee a similar outcome.
Read the default provision alongside the monthly payment.
The monthly amount may look manageable while the consequences of a missed installment receive less attention. This proposal puts the grace period and the larger default balance in a separate clause. A review should connect the due date, receipt of funds, allowed payment method, credits and consequences of a late or incomplete remittance.
The proposal's dismissal recital also needs context. A settlement document, a filed dismissal and a final release are different records. Ask which claims are being resolved, which parties receive a release, whether any UCC filing remains and what documents will demonstrate completion.
Other provisions in the supplied proposal concern governing law, written modifications and non-disparagement. A payment summary cannot replace review of those terms. The complete executed agreement, any amendments and the current court record are needed before drawing conclusions about enforceability or closure.
Four practical first steps.
- Check for a court deadline.If you received court papers, identify where the case is filed and when a response is due. Settlement discussions do not automatically extend a deadline.
- Put the records in one place.Collect the agreement, payment history, bank statements, and every notice. Preserve emails and texts, including any proposed settlement terms.
- Review a proposed change before signing.A new agreement, acknowledgment, release, or guarantee can affect your rights and obligations. Have its terms reviewed in context.
- Discuss a plan for your actual situation.Ask which legal or negotiation options fit the documents, cash flow, and litigation status—and what representation would cost.
Credibly questions, answered.
Why does my paperwork say Retail Capital rather than Credibly?
The example names Retail Capital LLC doing business as Credibly. Credibly's public disclosures also identify more than one entity. Match the exact legal name to your agreement, payment records, assignments and court caption.
Does the $80,000 proposal establish what Credibly will accept in my case?
No. It concerns one matter and the supplied copy is unsigned. It is not a current offer, standard settlement amount or promised result.
Does a dismissal mean all payment and lien issues are resolved?
That cannot be concluded from a recital alone. The dismissal document, its terms, the settlement obligations and the separate lien records all need review.
What should I bring if Credibly has sued my business?
Bring the entire summons and complaint, how and when they were received, the funding agreement, guarantees and payment records. Identify any hearing date immediately when requesting a consultation.
What does the free case review cover?
The initial consultation can address your funding agreement, payment pressure, collection communications or case status. Any retained legal-service fees are separate and addressed in the engagement terms.
Let’s review your Credibly matter.
Tell us about the payment demand, proposed agreement or court papers you need help understanding.
General information, not legal advice. Options depend on the agreements, facts, applicable law, and procedural history. No result is guaranteed. Contacting the firm does not create an attorney-client relationship or extend a deadline. Business Debt Law Group provides legal services; it does not provide or arrange financing.