GFE NY LLC MCA lawsuit or a lump-sum settlement proposal?
A one-payment proposal still needs a careful review of timing, default consequences and releases. Confirm exactly which GFE entity and obligations are involved before relying on a settlement example or sending funds.
Free MCA review or case evaluation.
No lawsuit is required to ask for help.
The GFE NY file
The public excerpt names GFE NY, LLC as purchaser under a receivables purchase agreement. The seller and guarantor information is redacted. Similar initials or a shared business address do not by themselves establish that another company owns or can settle your obligation.
This example concerns a single lump-sum payment, not a long installment plan. It also includes time-of-the-essence language, default notice and cure provisions, and releases with conditions that need to be read together.
The visible page ends while describing the purchaser’s release after fulfillment and clearance of payments. Because that provision continues beyond the excerpt, the full scope and final effect cannot be established from this page alone.
- Named purchaser
- GFE NY, LLC
- Payment structure in the example
- One lump-sum payment on a redacted date
- Release review
- Separate seller and purchaser provisions; one continues beyond the excerpt
- Independent legal representation
- Business Debt Law Group is not affiliated with, endorsed by, or acting for GFE NY LLC.
A single payment with conditions beyond the amount
The excerpt states a $56,270.76 outstanding balance and describes a $16,500 lump-sum settlement. It provides for email notice and a one-day cure period after receipt, with the original outstanding balance less settlement payments becoming due if the described default remains uncured. The sellers’ release appears on the page; the purchaser’s conditional release begins near its end. The excerpt does not prove that either payment or final release occurred.
See more MCA settlement examples ↗
Partial, redacted excerpt from one matter. Other pages, amendments and later events may affect these terms. This discussion does not summarize the complete agreement or case. Acceptance, completed payment, releases and the final outcome require verification from the complete records. This is not a standard offer or promised result. Past results do not guarantee a similar outcome.
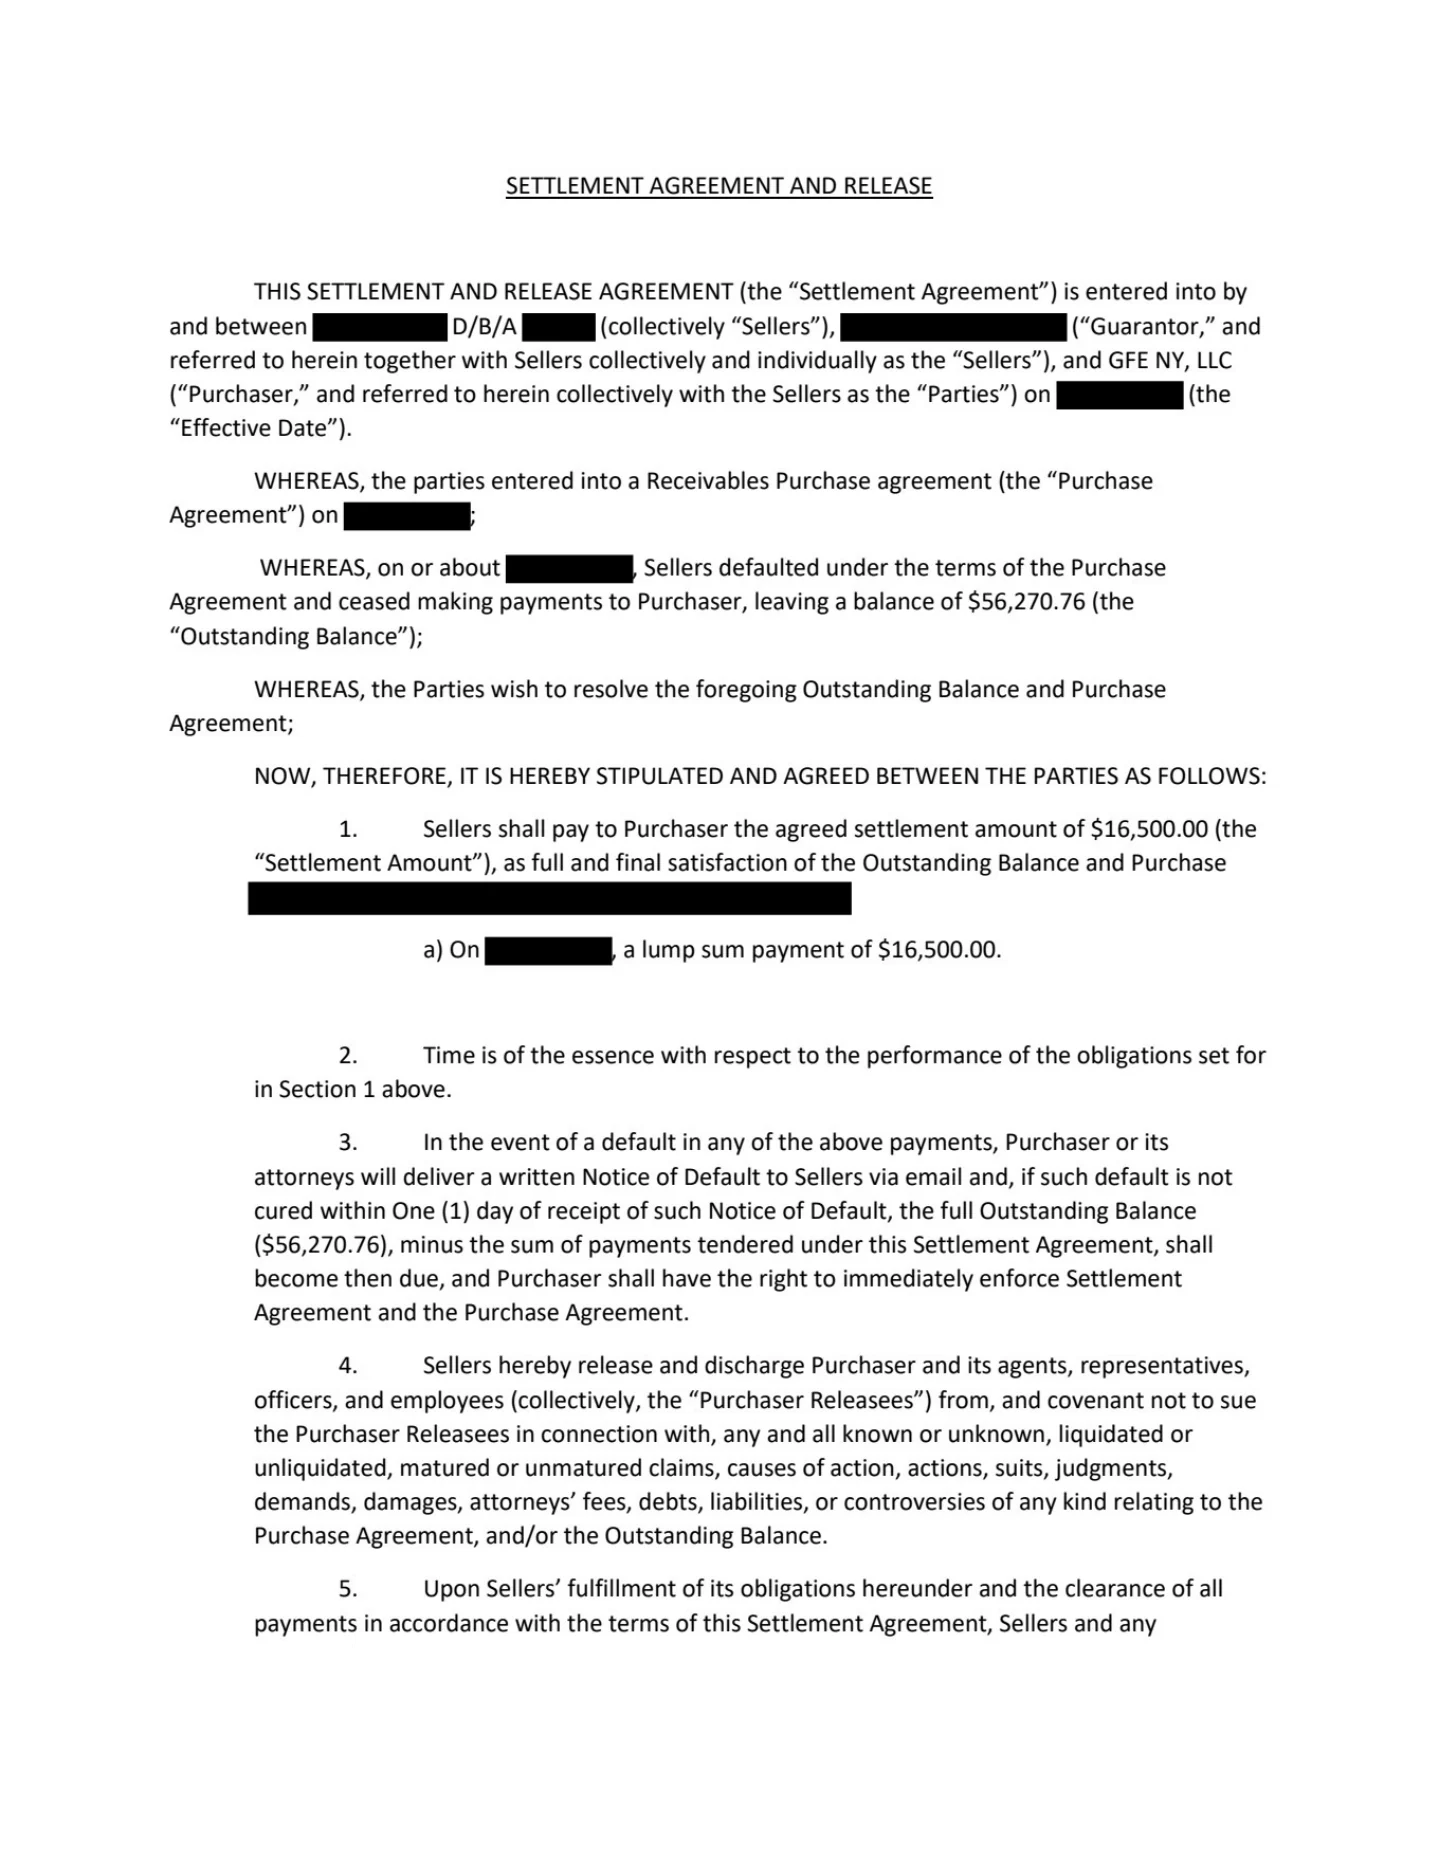
Payment, clearance and release are separate milestones
Before committing to a lump sum, confirm the source of funds, the due date, the required transfer method and when receipt counts under the complete terms. A payment initiated on the due date may not be the same as funds received or cleared. Resolve that timing question in writing rather than relying on a bank’s estimated transfer date.
Review the scope and sequence of releases for every party, including any guarantor. A merchant’s release of claims and a funder’s later conditional release need not take effect simultaneously. Read the continuation of the provision and all amendments before saying the account, guaranty or case has been fully resolved.
Keep the exact legal entity tied to the account. If another servicer, assignee or similarly named business communicates about the matter, request records of its role and authority. That prevents an agreement with one party from being mistakenly treated as a resolution of a different obligation.
Where does your GFE NY matter stand?
MCA payments are too much
Assess whether a lump sum is feasible without creating another unaffordable MCA commitment.
Receivables or accounts are affected
Match each third-party notice to the exact GFE entity and the obligation it claims to enforce.
Court papers have arrived
Check court deadlines independently while counsel reviews the settlement’s payment and release conditions.
Four practical first steps.
- Check for a court deadline.If you received court papers, identify where the case is filed and when a response is due. Settlement discussions do not automatically extend a deadline.
- Put the records in one place.Collect the agreement, payment history, bank statements, and every notice. Preserve emails and texts, including any proposed settlement terms.
- Review a proposed change before signing.A new agreement, acknowledgment, release, or guarantee can affect your rights and obligations. Have its terms reviewed in context.
- Discuss a plan for your actual situation.Ask which legal or negotiation options fit the documents, cash flow, and litigation status—and what representation would cost.
GFE NY MCA questions, answered.
Does one lump-sum payment make the paperwork simple?
Not necessarily. Receipt timing, default terms, guarantor obligations and releases still need review.
Does the excerpt show a completed $16,500 settlement?
It describes terms. It does not establish acceptance, cleared payment or completion.
Are all companies using GFE in their name interchangeable?
No. Match the exact legal entity and any documented assignment or servicing role to your account.
Can the purchaser’s complete release be read here?
No. The visible provision continues beyond the excerpt. The remaining pages and later records are necessary.
What does the free MCA review cover?
The initial consultation can address your MCA agreement, payment pressure, collection communications or case status. Consultations are free. Any retained legal-service fees are separate and addressed in the engagement terms.
Let’s review your GFE NY MCA.
Tell us about the payment demand, proposed agreement or court papers you need help understanding.
General information, not legal advice. Options depend on the agreements, facts, applicable law, and procedural history. No result is guaranteed. Contacting the firm does not create an attorney-client relationship or extend a deadline. Business Debt Law Group provides legal services; it does not provide or arrange financing.