Granite Merchant Funding MCA lawsuit concerns or an approved settlement offer?
An approved offer is not the same as a completed resolution. A Granite settlement letter should be checked for the payment-receipt deadline, the account covered and the records that will confirm closure.
Free MCA review or case evaluation.
No lawsuit is required to ask for help.
The Granite file
Granite Merchant Funding’s website describes revenue-based financing. BDLG’s public library contains correspondence using the Granite Merchant Funding name and setting out terms for resolving a particular account. Your original agreement remains the source for the precise legal entity and transaction terms.
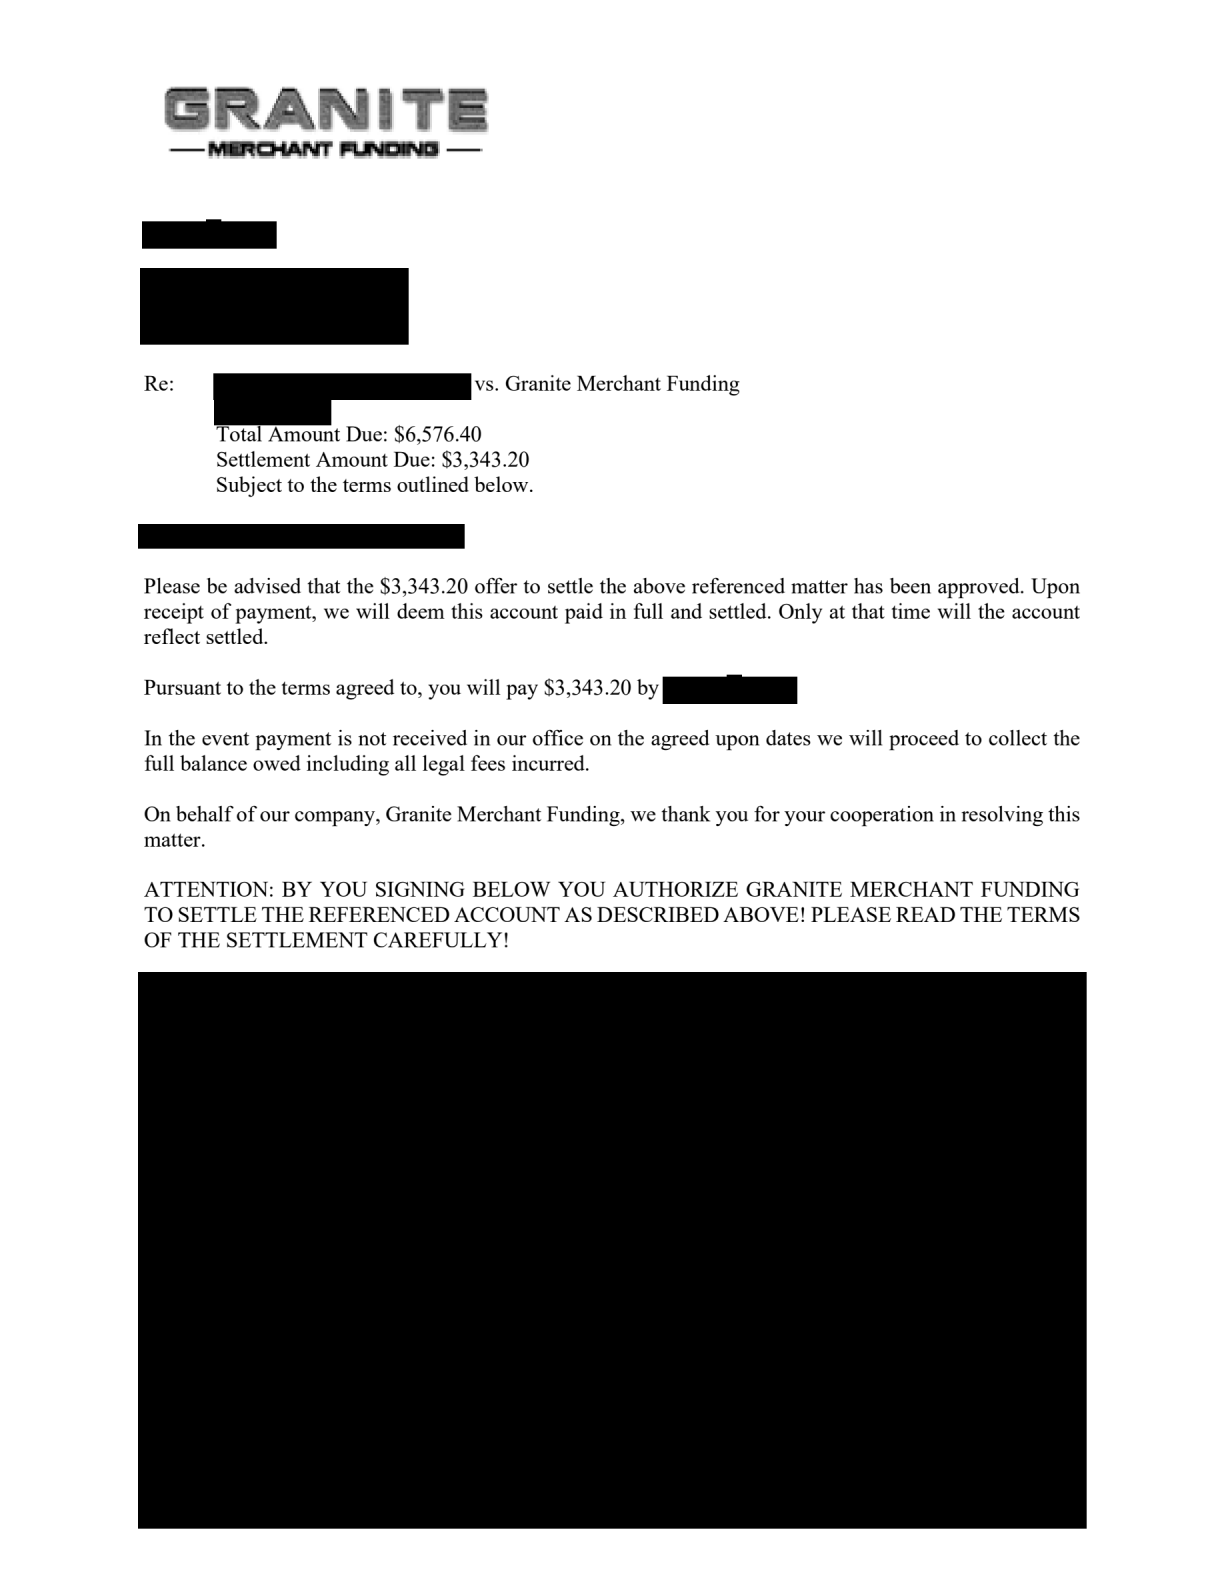
The letter says an offer has been approved, but expressly ties the account’s settled status to receipt of payment. That distinction prevents the document from being mistaken for a receipt or a confirmation that the merchant already performed.
The public copy does not establish the complete litigation history, any guarantee release or a credit-reporting outcome. A case-style reference in correspondence is not a substitute for checking whether a complaint or judgment actually exists.
Sources: Granite Merchant Funding’s description of revenue-based financing
- Name on the correspondence
- Granite Merchant Funding
- Status shown
- Approval of stated terms, conditioned on receipt of payment
- Records to match
- Agreement, account reference and any separate court file
- Independent legal representation
- Business Debt Law Group is not affiliated with, endorsed by, or acting for Granite Merchant Funding.
Approval and payment completion are different events
The letter lists $6,576.40 due and approves a $3,343.20 settlement offer subject to payment by a redacted date. It says the account would reflect settled status only after payment is received, and addresses collection of the full balance and legal fees if payment is not received as agreed. It does not itself prove timely payment, account closure or the enforceability of every stated consequence.
See more MCA settlement examples ↗
Partial, redacted excerpt from one matter. Other pages, amendments and later events may affect these terms. This discussion does not summarize the complete agreement or case. Acceptance, completed payment, releases and the final outcome require verification from the complete records. This is not a standard offer or promised result. Past results do not guarantee a similar outcome.
Ask for the record that confirms the offer was performed
Match the approved amount to the particular account. If there were renewals or multiple advances, identify whether the letter covers just one obligation and whether a guarantor or separate proceeding needs additional closing language. Keep the signed acceptance with the complete offer and any written changes.
Confirm what counts as timely receipt and retain the transfer confirmation and receiving-party acknowledgment. A debit from your bank account may be useful evidence, but it does not answer every question about posting, clearance or application to the intended account.
Request the appropriate final accounting or closure confirmation after performance. The letter’s reference to an account being settled should not be presented as a promise about a consumer or business credit report. If reporting is an issue, identify the actual report and the specific information being furnished before discussing a correction.
Where does your Granite matter stand?
MCA payments are too much
Review the proposed lump sum and any other MCA obligations before committing funds.
Receivables or accounts are affected
Keep the approved offer separate from evidence that payment was received and applied.
Court papers have arrived
Check the docket if you have a summons or judgment; the letter alone does not establish case status.
Four practical first steps.
- Check for a court deadline.If you received court papers, identify where the case is filed and when a response is due. Settlement discussions do not automatically extend a deadline.
- Put the records in one place.Collect the agreement, payment history, bank statements, and every notice. Preserve emails and texts, including any proposed settlement terms.
- Review a proposed change before signing.A new agreement, acknowledgment, release, or guarantee can affect your rights and obligations. Have its terms reviewed in context.
- Discuss a plan for your actual situation.Ask which legal or negotiation options fit the documents, cash flow, and litigation status—and what representation would cost.
Granite MCA questions, answered.
Does approval mean the Granite account is already settled?
No. This letter conditions settled status on receiving the agreed payment.
Does the letter promise a credit-report change?
The visible text addresses account status, not a particular bureau or reporting result.
Can another business use the $3,343.20 offer?
No. It was approved for a specific account and deadline. It is not a standard offer.
Does the letter prove a lawsuit was filed?
No. Verify any case through the court papers and docket rather than the correspondence’s reference line.
What does the free MCA review cover?
The initial consultation can address your MCA agreement, payment pressure, collection communications or case status. Consultations are free. Any retained legal-service fees are separate and addressed in the engagement terms.
Let’s review your Granite MCA.
Tell us about the payment demand, proposed agreement or court papers you need help understanding.
General information, not legal advice. Options depend on the agreements, facts, applicable law, and procedural history. No result is guaranteed. Contacting the firm does not create an attorney-client relationship or extend a deadline. Business Debt Law Group provides legal services; it does not provide or arrange financing.