LiteFund Solutions MCA lawsuit or a settlement awaiting signatures?
Before relying on a proposed settlement, confirm who has signed, which instructions apply and what the judgment language actually allows.
Free MCA review or case evaluation.
No lawsuit is required to ask for help.
The LiteFund file
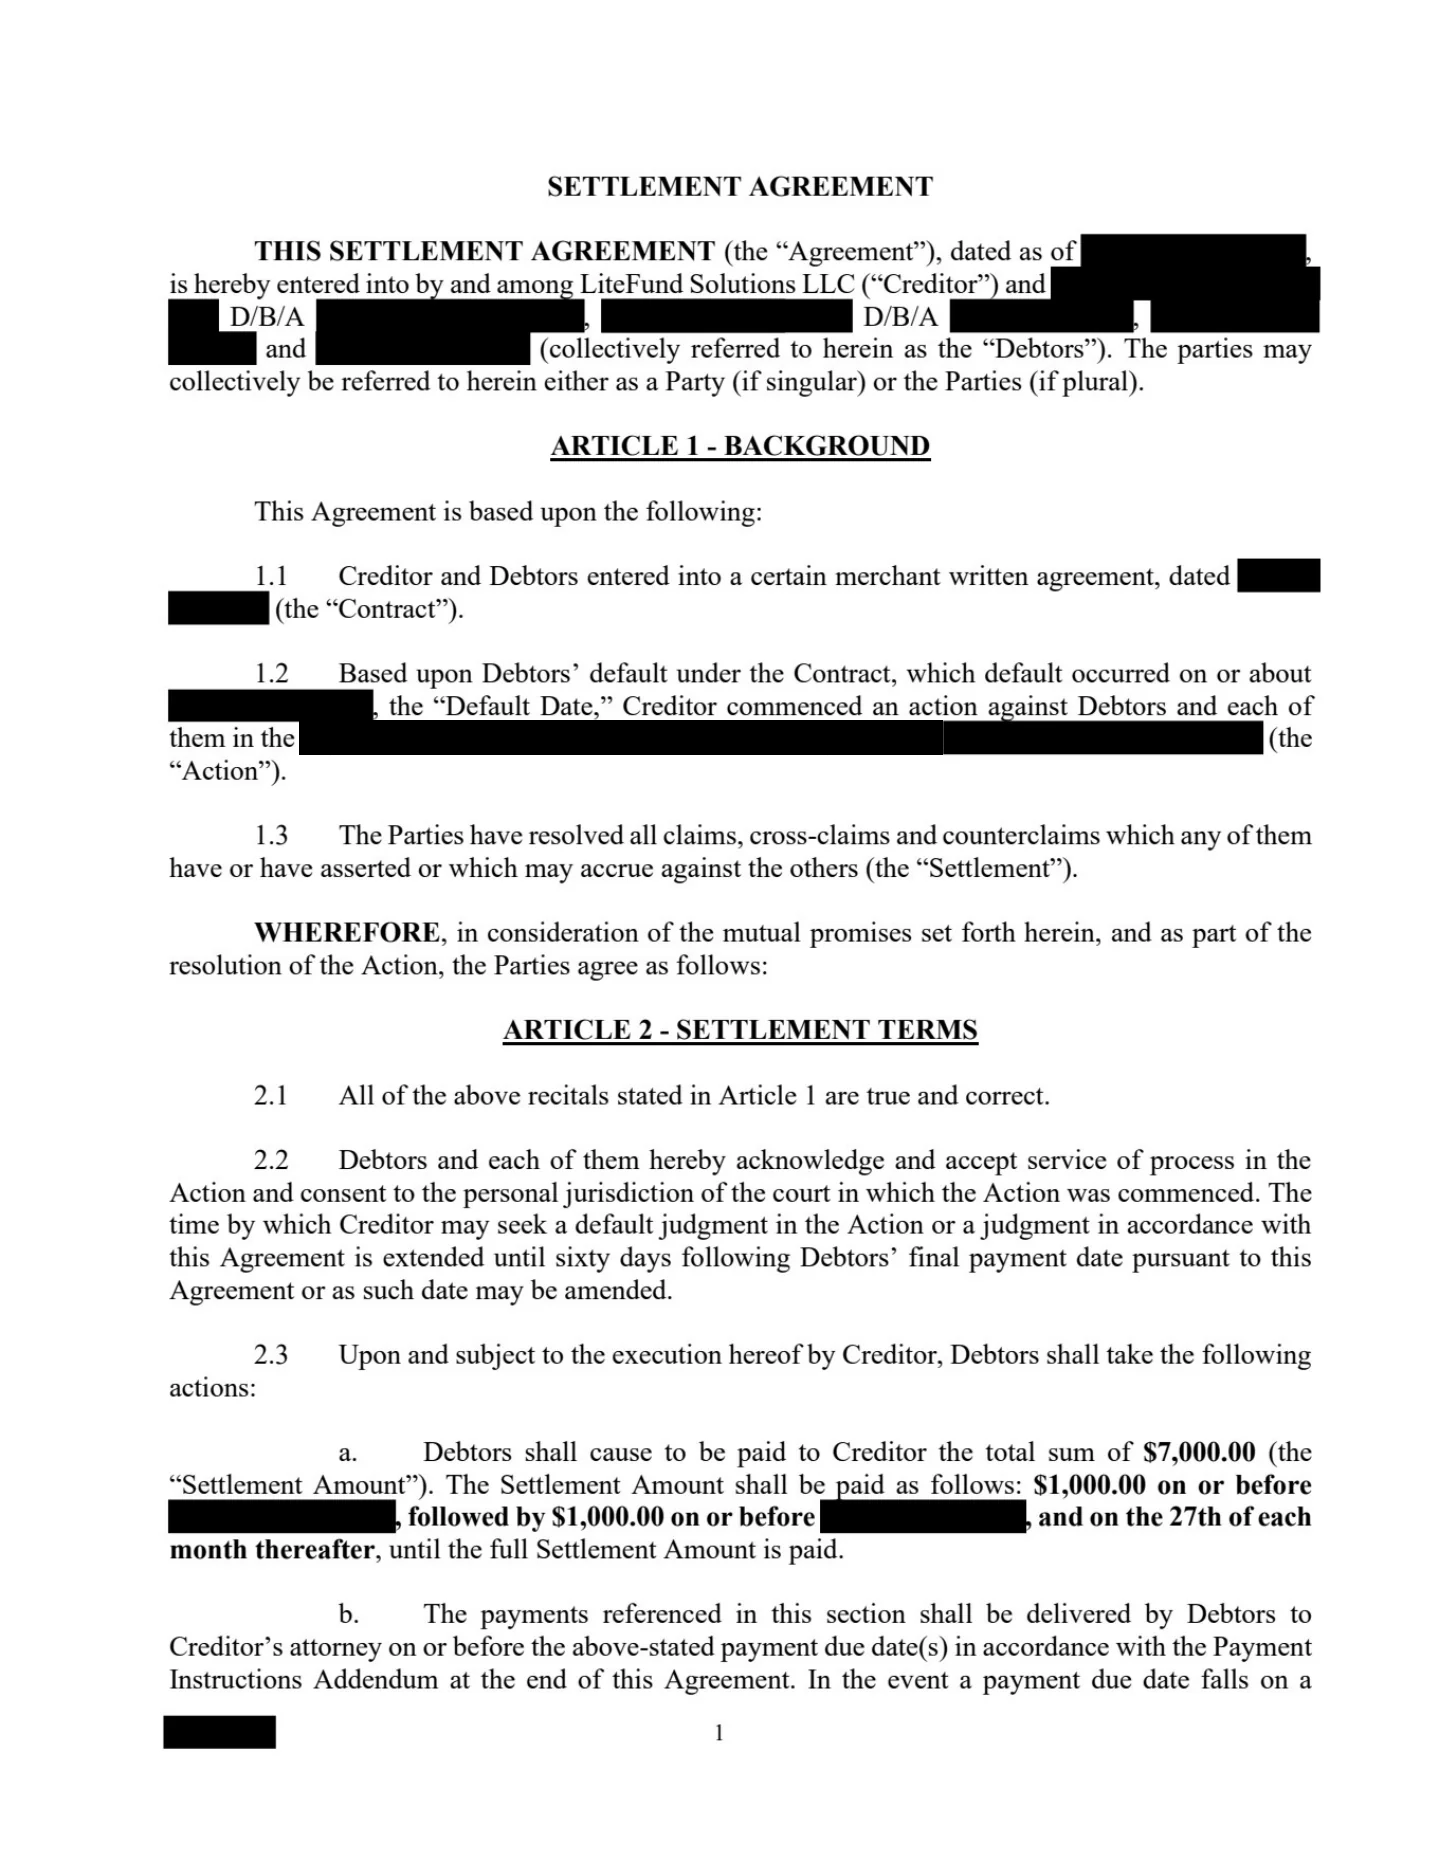
The redacted record in BDLG’s library identifies LiteFund Solutions LLC as the creditor and refers to a written merchant agreement and court action. It sets out $7,000 settlement terms but does not show an original claimed balance sufficient to verify a reduction percentage.
Two details matter beyond the dollar figure: the agreement is subject to the creditor’s execution, and the payment instructions are in an addendum that is not visible in the excerpt. A proposal and a complete executed agreement are different records.
The excerpt also includes a 60-day clause concerning the creditor’s time to seek judgment. It should not be read as an extra 60 days for the merchant to make each payment.
- Creditor named
- LiteFund Solutions LLC
- Settlement amount shown
- $7,000
- Key records to obtain
- Creditor’s execution and referenced payment addendum
- Independent legal representation
- Business Debt Law Group is not affiliated with, endorsed by, or acting for LiteFund Solutions.
A $7,000 schedule with conditions outside the headline amount
The excerpt provides an initial $1,000 payment, another $1,000 on a specified date and further $1,000 payments on the 27th of each month until the settlement amount is paid. It states that the agreement is subject to the creditor’s execution and references payment instructions in an addendum. The redacted dates and missing pages prevent this image from serving as complete payment instructions.
See more MCA settlement examples ↗
Partial, redacted excerpt from one matter. Other pages, amendments and later events may affect these terms. This discussion does not summarize the complete agreement or case. Acceptance, completed payment, releases and the final outcome require verification from the complete records. This is not a standard offer or promised result. Past results do not guarantee a similar outcome.
The 60-day clause is not a payment grace period
Read the subject of the deadline. In this excerpt, the 60-day language concerns an extension of the creditor’s time to seek default judgment or judgment after the final payment date. It does not say that the merchant can make installments 60 days late. Counsel should review that provision alongside the default and enforcement terms.
Obtain the version signed by all required parties, including the creditor where execution is a condition. Confirm that schedules and addenda are attached and match the document you reviewed. A detached signature page or emailed summary may omit terms that affect how the settlement operates.
Verify payment instructions through a known, independently confirmed contact before sending money. Keep the agreed instructions and each receipt with the executed agreement. If the payment destination changes, ask who authorized the change and obtain a reliable written confirmation rather than assuming a new email overrides the addendum.
Where does your LiteFund matter stand?
MCA payments are too much
Check the actual initial and recurring dates, and whether the agreement has satisfied its execution conditions.
Receivables or accounts are affected
Locate the complete agreement’s provisions on holds, notices and any releases; the excerpt does not answer every collection question.
Court papers have arrived
Review the case docket and judgment clause without treating settlement language as an automatic extension of your response deadline.
Four practical first steps.
- Check for a court deadline.If you received court papers, identify where the case is filed and when a response is due. Settlement discussions do not automatically extend a deadline.
- Put the records in one place.Collect the agreement, payment history, bank statements, and every notice. Preserve emails and texts, including any proposed settlement terms.
- Review a proposed change before signing.A new agreement, acknowledgment, release, or guarantee can affect your rights and obligations. Have its terms reviewed in context.
- Discuss a plan for your actual situation.Ask which legal or negotiation options fit the documents, cash flow, and litigation status—and what representation would cost.
LiteFund MCA questions, answered.
Does the 60-day provision give me extra time to pay?
The visible provision concerns the creditor’s time to seek judgment, not a merchant payment grace period.
Is the proposal effective before LiteFund signs?
The excerpt makes creditor execution a condition. The complete documents and circumstances require review.
What percentage was saved in the example?
The visible excerpt does not establish the original claimed balance needed for that calculation. This guide does not infer one.
Where are the payment instructions?
The excerpt refers to an addendum. Obtain the complete executed package and verify the destination before relying on it.
What does the free MCA review cover?
The initial consultation can address your MCA agreement, payment pressure, collection communications or case status. Consultations are free. Any retained legal-service fees are separate and addressed in the engagement terms.
Let’s review your LiteFund MCA.
Tell us about the payment demand, proposed agreement or court papers you need help understanding.
General information, not legal advice. Options depend on the agreements, facts, applicable law, and procedural history. No result is guaranteed. Contacting the firm does not create an attorney-client relationship or extend a deadline. Business Debt Law Group provides legal services; it does not provide or arrange financing.