OnDeck Lawsuit or business loan payment problems?
An OnDeck lawsuit or payment demand needs a review of the actual loan, the payment record and any personal guarantee. Our attorneys help business owners assess their response, including when OnDeck payments overlap with separate MCA obligations.
Free initial case review.
No lawsuit is required to ask for help.
The OnDeck file
OnDeck describes its current U.S. products as business term loans and business lines of credit. It is part of Enova International. This guide concerns existing debt and legal disputes; Business Debt Law Group does not offer or arrange financing.
OnDeck’s published terms identify On Deck Capital, Inc., ODK Capital, LLC and affiliates as operating under the OnDeck brand. Its disclosures say the lender may be an OnDeck company or Celtic Bank, depending on the transaction. Match the name in your agreement with the creditor named in a demand or complaint. A familiar brand does not replace the need to identify the particular account and party asserting the claim.
Daily or weekly withdrawals do not, by themselves, make an agreement an MCA. If you also have receivables-purchase agreements, keep their terms and payment records separate from an OnDeck loan. The contract type affects which questions an attorney needs to investigate.
Public sources: OnDeck company information · OnDeck product and account FAQs · OnDeck business loan disclosures · OnDeck line-of-credit information
- Product check
- Current OnDeck offerings include business term loans and revolving lines of credit; do not assume they are MCAs.
- Account check
- Separate each term loan, renewal and credit-line draw before comparing payments with a collection demand.
- Security and guarantees
- Review the signed security agreement and any personal guarantee separately from a UCC filing.
- Independent legal representation
- Business Debt Law Group is not affiliated with, endorsed by, or acting for OnDeck.
Start with the account behind the OnDeck demand.
Term loan: reconcile the balance
Gather the signed agreement, funding statement, repayment schedule and complete payment history. Ask for an itemized account of principal, interest, fees and credits. If a renewal paid an older balance, identify that payoff and which agreement the present demand concerns. A bank withdrawal list alone may not explain the creditor's calculation.
Line of credit: trace individual draws
OnDeck describes a revolving credit line that permits new draws as availability returns. A repayment followed by another draw can make the current balance difficult to reconstruct. Collect monthly statements and draw confirmations, and distinguish the credit limit from the amount actually borrowed or claimed.
Lawsuit: match the parties and documents
Keep the summons, complaint, service records and exhibits together. Check whether the business, an individual guarantor or both are named. Tell your attorney about any hearing, judgment or bank notice immediately. A payment-support conversation is separate from responding to court papers.
OnDeck / ODK Capital settlement example
The agreement names ODK Capital, LLC, an entity identified in OnDeck’s published terms as operating under the OnDeck brand.
$58,004.62
$46,000
The judgment would be filed only upon default. Settlement depends on compliance with the payment terms; payment completion is not represented.
The payment schedule calls for $767 monthly installments until the $46,000 total is paid. The conditional judgment is subject to payment credits and specified fees, costs and interest. Dismissal depends on timely completion of all payments.
Past results do not guarantee a similar outcome. Every matter depends on its agreements, facts and procedural history. This excerpt shows source pages 1–2; identifiers and remittance details are redacted, and signature and audit pages are omitted.
A workable settlement needs clear closing terms.
If you are discussing an OnDeck settlement, review more than the proposed payment amount. Identify which account is covered, who is released, when any release becomes effective and what happens if an installment is late. Check whether interest or fees continue and whether an existing judgment or lien remains until specified conditions are met.
Compare the stated total with every installment and final payment. If the document contains a typo, inconsistent amount or unclear due date, request a corrected written agreement before relying on it. A proposed discount is different from a completed settlement, and no particular reduction or payment plan is guaranteed.
OnDeck's published FAQ directs borrowers to request a UCC release in writing after full loan repayment. A negotiated settlement may have different closing conditions. Have the actual agreement reviewed for the required release documents and timing; keep proof of payment and confirmation of any filing or court disposition.
A UCC financing statement, a personal guarantee and a court judgment are different records. Resolving one does not establish that every related obligation or restriction has ended. If a bank account is frozen, preserve the bank's notice so the legal basis can be identified.
Four practical first steps.
- Check for a court deadline.If you received court papers, identify where the case is filed and when a response is due. Settlement discussions do not automatically extend a deadline.
- Put the records in one place.Collect the agreement, payment history, bank statements, and every notice. Preserve emails and texts, including any proposed settlement terms.
- Review a proposed change before signing.A new agreement, acknowledgment, release, or guarantee can affect your rights and obligations. Have its terms reviewed in context.
- Discuss a plan for your actual situation.Ask which legal or negotiation options fit the documents, cash flow, and litigation status—and what representation would cost.
OnDeck questions, answered.
Is an OnDeck loan a merchant cash advance?
OnDeck currently markets U.S. business term loans and lines of credit. Review your signed documents to identify the transaction. Frequent automatic payments do not alone establish an MCA. If your business has both loans and MCAs, an attorney can review how the separate obligations affect your situation.
What should I do if OnDeck sues my business?
Preserve the complete court papers and the information showing when and how they were served. Request a legal review promptly to identify the response deadline, named defendants, claimed balance and available options. Do not assume that settlement discussions stop the case or extend a deadline.
Can I ask for payment relief before a lawsuit?
OnDeck's FAQ provides payment-support contacts. You can also ask BDLG to review your agreement and any proposed change before signing. Whether a modification or settlement is available depends on the account and creditor's agreement; contacting either party does not itself change your payment obligations.
Does a business-asset lien mean the owner's home is collateral?
OnDeck's FAQ distinguishes its general business-asset lien from personal assets pledged as collateral. A personal guarantee is a separate issue and may create individual liability under its terms. An attorney should examine both documents and any collection papers before advising on the owner's exposure.
Does paying an OnDeck settlement automatically remove a UCC filing?
Do not assume so. Review the settlement's release requirements, who must submit the filing and when. Keep the payoff or settlement confirmation and verify the filing record afterward. OnDeck's full-repayment instructions do not replace the terms of a separately negotiated agreement.
Can you review OnDeck debt alongside my MCA payments?
Yes. Business Debt Law Group reviews existing business-debt disputes, including situations involving loans and separate MCA agreements. Provide each contract and payment schedule so the review distinguishes the obligations. Any representation depends on the matter, conflicts and applicable court-admission requirements.
What does the free case review cover?
The initial consultation can address your funding agreement, payment pressure, collection communications or case status. Any retained legal-service fees are separate and addressed in the engagement terms.
Let’s review your OnDeck matter.
Tell us about the payment demand, proposed agreement or court papers you need help understanding.
General information, not legal advice. Options depend on the agreements, facts, applicable law, and procedural history. No result is guaranteed. Contacting the firm does not create an attorney-client relationship or extend a deadline. Business Debt Law Group provides legal services; it does not provide or arrange financing.
OnDeck / ODK Capital — redacted settlement excerpt
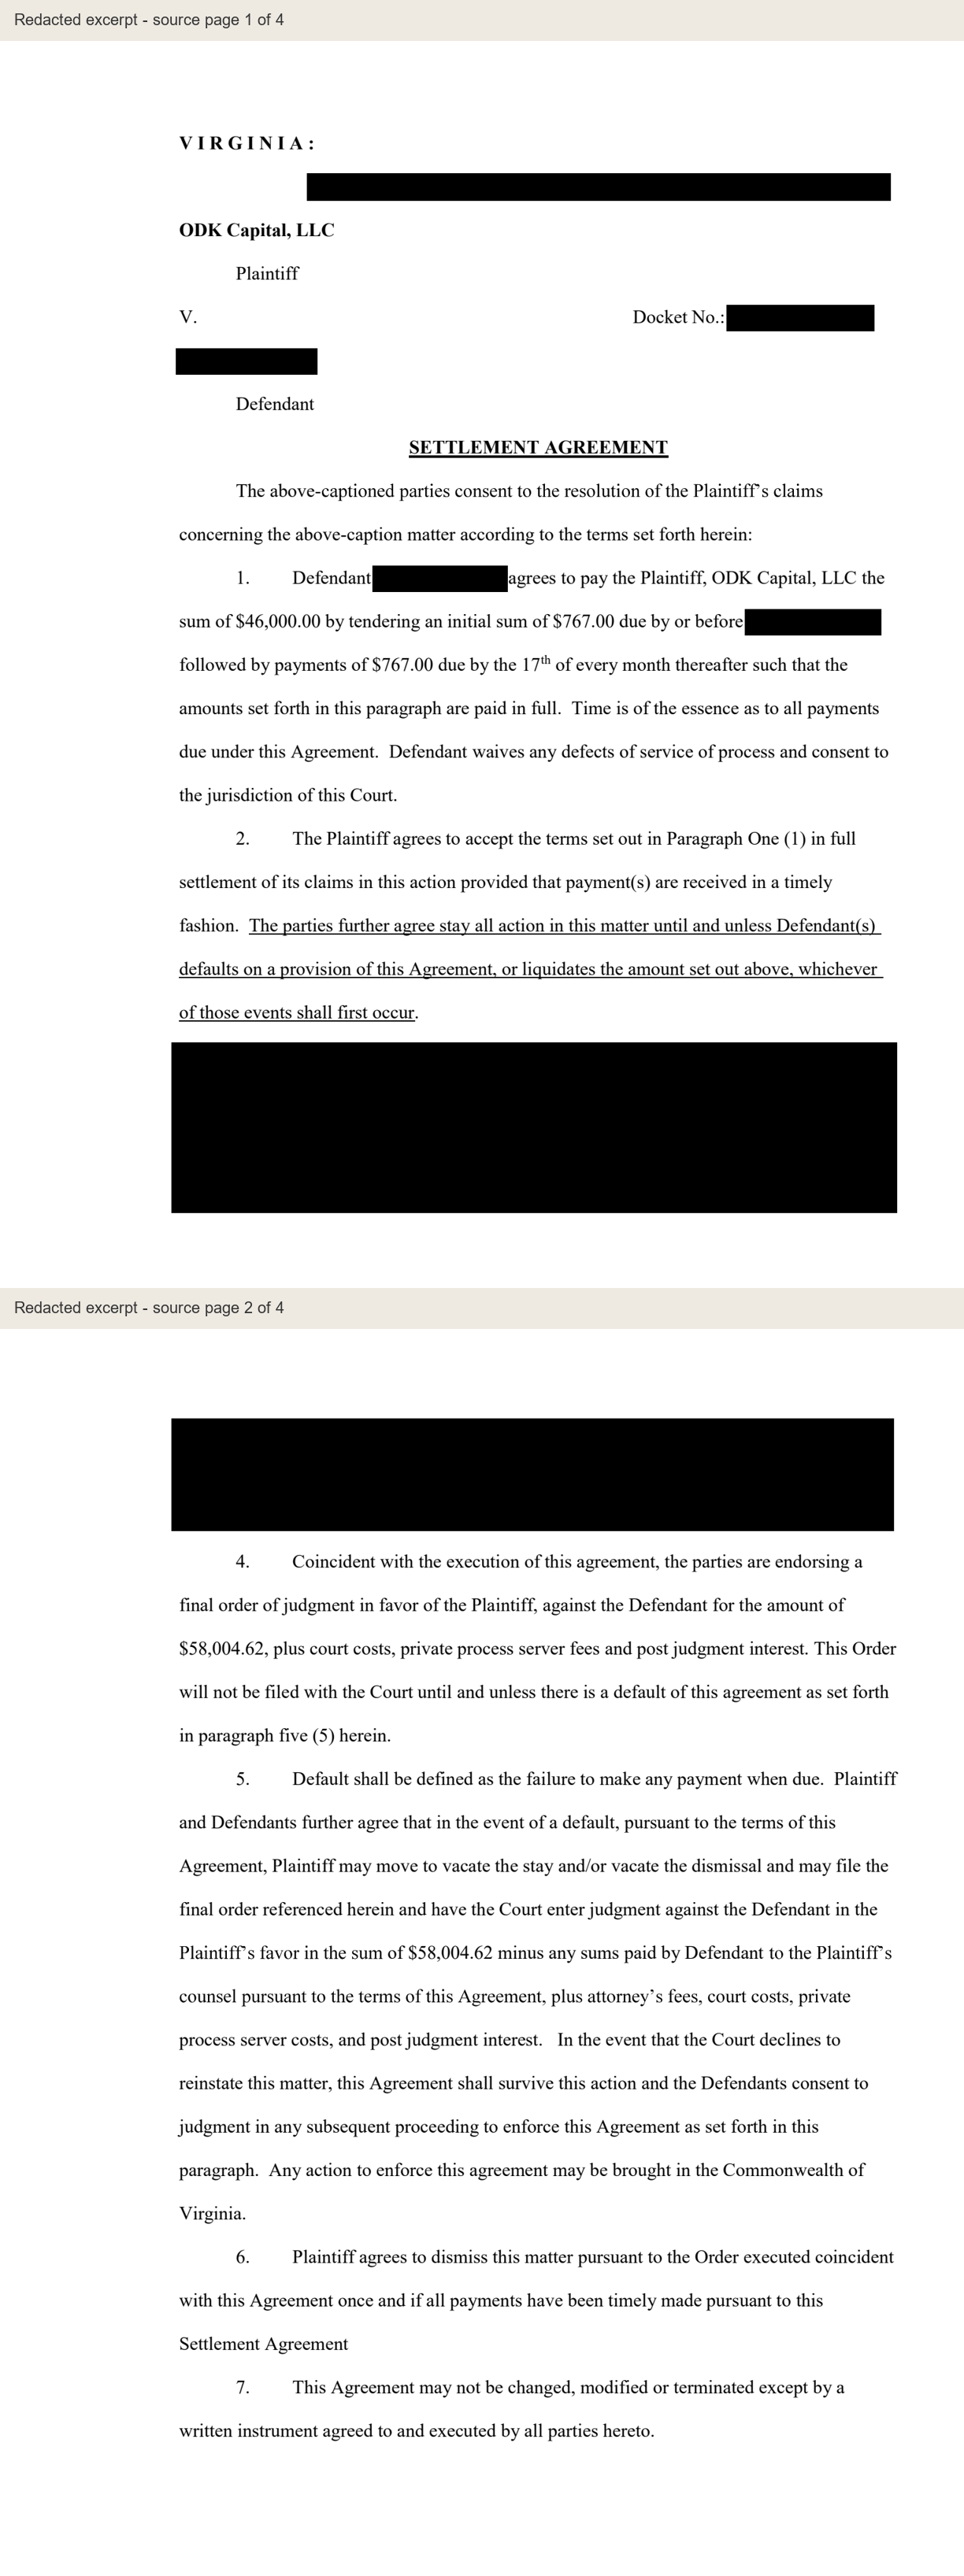
Client identifiers and remittance details are redacted. Signature and audit pages are omitted. This excerpt does not establish payment completion or dismissal. Past results do not guarantee a similar outcome.